Did you know a one-percentage-point shift in government debt returns can change living costs for millions of Americans? In 2026, the financial landscape remains closely tied to these market measures. We define Bond Yield as the annual return an investor earns by lending capital to an entity.
Understanding this concept matters to anyone involved in Fixed-Income Investing. When rates on a 30-year Treasury hit 5.3%, they spread through the economy. These changes affect mortgage payments, local government budgets, and grocery prices.
We believe tracking these shifts helps everyday investors navigate complex financial conditions. By understanding how this Bond Yield works, you gain a clearer view of your economic future.
Key Takeaways
- It represents the interest rate earned on debt securities.
- These figures dictate borrowing costs for home mortgages.
- Government spending plans often hinge on current market rates.
- Changes in these metrics impact the broader consumer price index.
- Smart investors use these data points to manage portfolio risk.
Understanding Bond Yield: A Simple Definition
For fixed-income securities, the Bond Yield shows the yearly return compared with the bond’s purchase price. It helps investors judge a bond’s expected annual income.
What Does Bond Yield Mean?
This measure shows the income from a bond investment. Imagine buying a bond with a face value of $1,000 that pays $50 in yearly interest. In this case, your Current Yield is 5%.
This percentage changes when the bond’s market price changes. Buying the same bond for $900, rather than $1,000, raises your return because you invest less. Understanding this relationship is vital for investors seeking higher income.
Key Components of Bond Yield
Several factors shape your return. The coupon rate is the fixed interest rate the issuer promises to pay. The market price shows what investors will pay for the bond today.
Time also matters. The maturity date shows how long you will hold the asset before receiving the principal. Together, these factors determine the total profit from your fixed-income investments.
Types of Bond Yields Explained
Investors compare performance in several ways. The Current Yield shows yearly income based on the current market price. This measure helps with short-term assessments.
In contrast, Yield to Maturity gives a broader view. It includes your total return when you hold the bond until it expires, including gains or losses from its purchase price. Choosing the right measure depends on your investment goals and time horizon.
The Importance of Bond Yield in Financial Markets
Government debt performance often shows the global financial system’s pulse. Market participants track these figures to judge economic health and future interest rates. These measures help explain forces guiding capital allocation worldwide.
How Bond Yield Affects Investment Decisions
When we assess opportunities, the Bond Yield helps compare different securities. It lets us weigh expected income against an asset’s risks. These figures show whether a bond rewards investors for duration and credit risk.
Investors use these calculations to choose among cash, stocks, and fixed-income products. Higher debt returns can seem more appealing than volatile equity markets. This strategic comparison helps build a balanced, resilient portfolio.
Bond Yield as an Economic Indicator
The Treasury Yield provides a key benchmark for financial markets. Because the government backs these securities, they set a low-risk standard for mortgage rates and corporate borrowing costs. We focus on the 10-year note because its deep liquidity makes it a reliable signal of market sentiment.
Shifts in these rates often show expectations about inflation and economic growth. A rising trend may signal a stronger economy, while a falling trend may show stability concerns. The table below shows how yield metrics shape our financial view.
| Metric | Primary Use | Market Impact |
|---|---|---|
| 10-Year Treasury Yield | Benchmark for loans | High influence on mortgages |
| Corporate Bond Yield | Risk assessment | Reflects company credit health |
| Municipal Bond Yield | Tax-exempt planning | Influences local infrastructure |
| Yield to Maturity | Total return projection | Guides long-term strategy |
Factors Influencing Bond Yield
To understand why yields move, examine the broader economy. Cyclical and structural forces shape earnings from fixed-income securities. Studying these forces clarifies each Bond Yield change.
Interest Rates and Their Impact
Central bank policy drives yield movements. When policymakers change short-term rates, markets react almost at once. Recent data suggests shifting short-term rate expectations caused about 50 basis points of recent yield increases.
Inflation’s Role in Bond Yield
Inflation acts like a silent tax on fixed-income returns. When prices rise faster than expected, future coupon payments lose real value. About 10 basis points of recent yield adjustments reflect changing inflation expectations and lost purchasing power.
Credit Risk and Bond Yield
Default risk is a key part of bond pricing. Investors require a term premium to commit capital for longer periods. Recent market analysis links about 20 basis points of yield growth to this premium and extra compensation for long-term debt.
A Bond Yield Calculation must include the link between fixed coupon payments and current market prices. When prices fall, yields rise to keep the market in balance. The following table shows how these factors affect the overall return profile.
| Factor | Primary Driver | Impact on Yield |
|---|---|---|
| Interest Rates | Monetary Policy | High sensitivity |
| Inflation | Purchasing Power | Moderate increase |
| Credit Risk | Default Probability | Risk premium adjustment |
| Term Premium | Time Horizon | Long-term compensation |
Together, these variables help keep markets efficient. By tracking them, investors can refine their approach to the Bond Yield Calculation and make wiser choices in a volatile economy.
Types of Bonds and Their Yields
Bonds differ, and their yields often reflect each issuer’s unique nature. In the fixed-income market, we must compare borrowers and the terms they offer lenders.
These differences help us choose assets that match our financial goals. We may seek safety or higher income, but issuer creditworthiness drives our return.
Government Bonds vs. Corporate Bonds
Government bonds are often seen as the safest because the state backs them with full faith and credit. In contrast, Corporate Bond Yields often rise to offset the risks of lending to private businesses.
When companies issue large amounts of new debt, they often offer higher rates to attract buyers. This change in Corporate Bond Yields reflects market demand for compensation when credit risk rises or economic conditions tighten.
“The bond market is the ultimate judge of economic reality, reflecting the true cost of capital across different sectors of the economy.”
Municipal Bonds and Their Unique Yields
Municipal bonds serve a different purpose. Local governments issue them to fund public projects, such as schools or infrastructure. They often attract investors because of possible tax benefits that may suit specific investors.
When we evaluate Municipal Bond Yields, we cannot consider the headline rate alone. We must calculate the after-tax return and compare these bonds with taxable alternatives in our portfolios.
Interest from many municipal bonds is exempt from federal income tax, so the effective yield may be higher than it first appears. Understanding these Municipal Bond Yields requires reviewing our personal tax bracket and the bond’s specific legal status.
| Bond Type | Primary Risk | Tax Status |
|---|---|---|
| Government | Low | Taxable |
| Corporate | Moderate/High | Taxable |
| Municipal | Low/Moderate | Often Tax-Exempt |
How Investors Use Bond Yield
Understanding bond yields is a key skill for anyone involved in Fixed-Income Investing. We use these measures to judge potential income and total portfolio return. Yield data helps us match assets with our financial goals and risk tolerance.
Assessing Return on Investment
When we assess a bond, we look beyond its coupon rate to find its true Return on Investment. We compare its current income with the security’s purchase price. This calculation shows whether the bond offers enough value for our capital.
We must also consider duration exposure when reviewing our holdings. Longer-term bonds often have larger price swings when interest rates change. We balance this risk with our need for steady income to keep our strategy strong.
The Role of Yield Curves in Strategy
The Bond Yield Curve is a vital map for our investment strategy. It compares yields for short-, intermediate-, and long-term bonds at one point in time. Its shape can show whether the market expects rates to rise or fall.
We use this information to build laddering strategies, which use bonds with staggered maturity dates. This approach helps manage interest-rate risk while keeping liquidity steady. Through careful Fixed-Income Investing, we can choose maturities that fit our time horizon and income needs.
Ultimately, the Bond Yield Curve guides our maturity choices. When the curve is steep, we may favor longer-term bonds to capture higher yields. A flat curve may lead us to keep duration shorter and protect capital from possible volatility.
Current Trends in Bond Yield for 2026
Investors are navigating a unique period as market forces reshape traditional expectations. In 2026, inflation concerns and changing central bank policies are interacting. These forces have created a volatile setting for anyone tracking debt instruments.
Expected Changes in Yield Rates
The Treasury Yield has moved higher as markets price in long-term economic changes. The 30-year rate remains near 5.25%, showing that investors want higher premiums for long-term exposure. This setting has made the Bond Yield Curve increasingly flat.
The flattening of the Bond Yield Curve mainly reflects the rapid rise in two-year yields. Short-term borrowing costs are responding more strongly to current monetary policy than long-term expectations. The following table shows recent changes in key benchmarks:
| Instrument | Current Rate | Trend |
|---|---|---|
| 2-Year Treasury | 4.85% | Rising |
| 10-Year Treasury | 5.10% | Stable |
| 30-Year Treasury | 5.25% | Steady |
Predictions from Economic Experts
Market analysts say cyclical pressures may ease, but support for Corporate Bond Yields remains strong. Experts believe companies with strong balance sheets will offer attractive returns despite economic uncertainty. This resilience can support investors seeking long-term income.
“The current market environment requires a disciplined approach, as the relationship between risk and reward continues to evolve in response to global fiscal policies.”
We expect Corporate Bond Yields to remain important for institutional investors balancing their portfolios. The Treasury Yield sets the market baseline, while the spread between government and private debt shows investor sentiment. A clear view of the Bond Yield path is essential through the rest of 2026.
Risks Associated with Bond Investments
Fixed-Income Investing requires you to understand risks that can reduce your returns. Bonds may seem more stable than stocks, but market volatility can still affect them. Recognizing these risks helps you build a stronger portfolio.
Interest Rate Risk
Interest rate risk is the most common challenge for bond investors. When market rates rise, the Bond Yield of newly issued securities becomes more attractive than older bonds. As a result, investors seek higher payouts elsewhere, and your existing bonds usually lose market value.
This inverse relationship means rising yields can reduce the market value of your current holdings. Inflation risk erodes the purchasing power of fixed interest payments over time. Liquidity risk can emerge if you must sell a bond quickly when few buyers exist.
Default Risk and Credit Ratings
Default risk means an issuer may fail to make promised payments. In Fixed-Income Investing, always assess the financial strength of the entity behind each bond. A higher promised income often warns of greater default exposure.
Credit rating agencies provide data that helps you assess this danger. A lower rating usually signals greater default risk, so issuers must offer a higher Bond Yield to attract investors. Always perform your due diligence by reviewing these ratings before committing capital to corporate or municipal debt.
Calculating Bond Yield: A Step-by-Step Guide
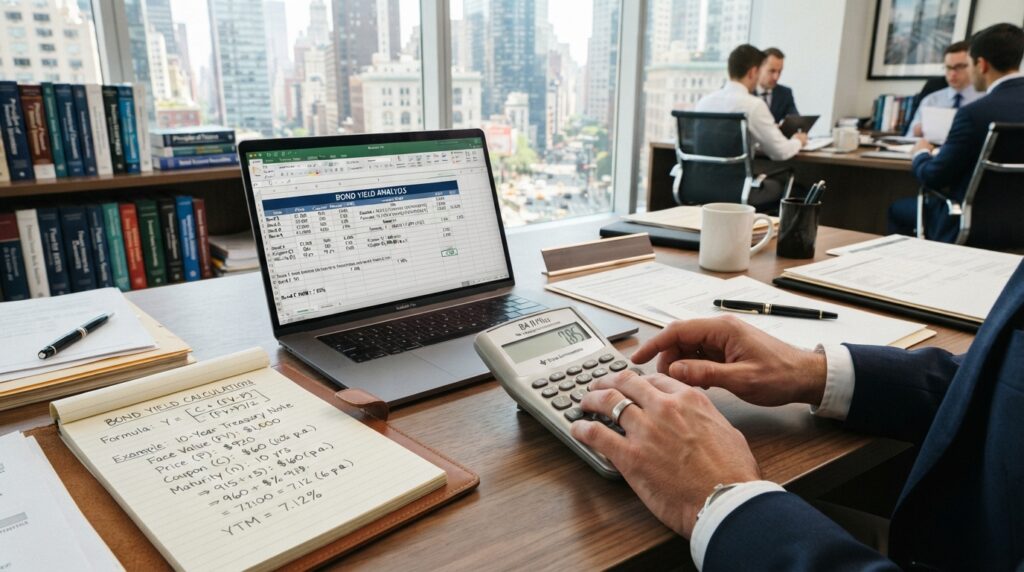
A precise Bond Yield Calculation helps you make better portfolio choices. Market headlines may simplify bond performance, but actual returns require several clear financial measures. Studying these numbers reveals the true value of fixed-income assets.
Current Yield vs. Yield to Maturity
To evaluate a bond, distinguish between two main measures. Current Yield compares the annual coupon payment with the bond’s current market price. Divide the annual dollar coupon by that price to estimate immediate income.
In contrast, Yield to Maturity (YTM) gives a fuller view of an investment. It estimates your total return if you hold the bond until it expires. This calculation includes several key factors:
- The annual coupon income received over the remaining term.
- The difference between the current purchase price and the face value.
- The total time remaining until the bond reaches maturity.
Current Yield is easy to calculate. The industry standard for comparing bonds is Yield to Maturity, which considers different prices and coupon rates. It captures the possible capital gain or loss when you hold the asset until the issuer repays the principal.
Using Online Calculators for Accurate Figures
Manual Bond Yield Calculation can cause errors, especially with compounding interest. Online financial calculators can quickly check your figures. They also test scenarios, such as how a purchase-price change affects your total return.
Still, enter every detail carefully. For accurate results, include these variables:
- Payment Frequency: Whether the bond pays interest semi-annually or annually.
- Call Provisions: Potential dates when the issuer might redeem the bond early.
- Taxes and Fees: Hidden costs that can reduce your net return.
These calculators provide estimates based on the information entered. Compare your results with official brokerage statements to confirm your Yield to Maturity projections. Combining manual understanding with digital tools helps you manage investments confidently.
Comparing Bond Yields Across Different Markets
When we study global finance, bond yields across borders show a complex mix of risk and reward. Investors often seek higher returns abroad, but they must study local economic conditions first. A yield percentage shows only one part of the total investment picture.
U.S. Bonds vs. International Bonds
In the United States, the Treasury Yield serves as a key benchmark for global debt markets. U.S. debt is often a safe haven, while foreign sovereign bonds may offer higher nominal rates for different risks. U.S. Corporate Bond Yields and Municipal Bond Yields use specific tax and regulatory rules that may not apply directly abroad.
When comparing these assets, we must consider credit quality and market structure. Local economic health and central bank policies strongly affect their appeal. Investors should not assume a higher foreign yield means a better deal; default or liquidity risks may be greater.
Understanding Currency Effects on Bond Yield
Currency changes strongly affect international investment performance. Even when a foreign bond offers high returns, a weaker local currency can reduce gains converted to U.S. dollars. The Bond Yield Curve can differ greatly between countries because of inflation expectations, fiscal policy, and central bank intervention.
These differences mean one nation’s curve may look unlike another’s. Successful investors watch these shifts closely because they show how a country manages debt and economic growth. By balancing yield potential with exchange-rate volatility, we can make informed decisions about global bond allocations.
The Future of Bond Yield in a Changing Economy
Understanding future bond yields means knowing how government policy and digital innovation connect. These global financial shifts will shape how we use Fixed-Income Investing in coming years.
Impact of Fiscal Policies on Bond Yield
Government fiscal decisions strongly affect market returns. When governments spend more and issue debt to cover deficits, credit markets may face a supply-demand imbalance.
More debt makes the government compete with corporate issuers for available capital. Investors may then demand higher returns because more bonds are available, pushing yields upward. Explore bonds and the yield curve to see how these macroeconomic forces interact.
The Role of Technology in Bond Markets
Technology is making bond markets more efficient. Electronic trading platforms now offer greater transparency and faster execution.
These advances support more precise Bond Yield Calculation. They help investors make confident, data-driven decisions. Automated portfolio tools also help people manage risk more effectively.
This table compares these modern shifts with traditional market practices:
| Feature | Traditional Approach | Modern Approach |
|---|---|---|
| Trading Method | Manual/Phone-based | Electronic/Automated |
| Data Access | Limited/Delayed | Real-time/Transparent |
| Yield Analysis | Basic Estimation | Advanced Algorithmic Modeling |
| Market Entry | Institutional Dominance | Broad Retail Access |
Ultimately, these technologies will continue to make Fixed-Income Investing more accessible. Better information and improved methods for Bond Yield Calculation can help us prepare portfolios for long-term success in a volatile economy.
Conclusion: The Vital Role of Bond Yield Awareness
Understanding debt markets helps you navigate modern finance. Every Bond Yield shift affects the economy, from personal mortgage rates to federal interest expenses. These changes provide vital signals for long-term wealth management.
Taking Informed Steps as an Investor
Compare Current Yield with Yield to Maturity to see your potential returns clearly. Assess duration and credit risk to match your Fixed-Income Investing choices with your time horizon. This disciplined approach helps protect your portfolio from unexpected market volatility.
Staying Updated on Market Changes
High borrowing costs affect household budgets and government spending throughout 2026. Watch inflation data, central bank policy decisions, and new issuance trends.
Regular attention helps keep your Fixed-Income Investing strategy resilient. By tracking each Bond Yield, you can adjust your strategy in a changing economic environment.