Did you know that the United States government manages over $30 trillion in total debt? This figure supports the world’s safest investment market.
We seek ways to grow savings while protecting our principal. Treasury Bonds help achieve this balance.
These government bonds offer long-term stability through fixed interest payments over several decades. Unlike common savings products, these securities trade on an active secondary market.
They carry unique risks, including changing interest rates and tax rules. Learning to purchase these assets can help build a strong financial future.
Key Takeaways
- Treasury Bonds provide a secure way to earn fixed interest over long periods.
- These government bonds are distinct from standard U.S. savings products.
- Investors can benefit from predictable income streams throughout the life of the asset.
- Market prices for these securities fluctuate based on current interest rates.
- Understanding tax treatment is essential for effective portfolio management.
What Are Treasury Bonds?
When people seek safe investments, they often consider Treasury bonds. These investments help the federal government fund operations and manage national debt.
Definition of Treasury Bonds
Treasury Bonds are long-term debt issued by the United States Department of the Treasury. They rank among the safest investments because the U.S. government backs them with its full faith and credit.
Investors buy these fixed-income securities for regular interest payments during a set period. When the bond matures, the government returns its original face value.
Types of Treasury Securities
The government offers many US Treasury securities for different investor needs. Although often grouped together, savings bonds are separate products with specific rules and purchase limits.
The following table shows the main government debt categories available to the public:
| Security Type | Maturity Range | Interest Payment |
|---|---|---|
| Treasury Bills | 4 to 52 weeks | Discounted price |
| Treasury Notes | 2 to 10 years | Fixed semi-annual |
| Treasury Bonds | 20 to 30 years | Fixed semi-annual |
| TIPS | 5, 10, or 30 years | Adjusted for inflation |
How Treasury Bonds Work
When you buy these fixed-income securities, you lend money to the government. The Treasury pays a fixed interest rate, called the coupon rate, every six months.
These US Treasury securities offer predictable income for long-term planning. At the end of the term, the government repays the full principal amount. This returns your initial investment in full.
Benefits of Investing in Treasury Bonds
When you focus on protecting capital, federal securities offer several useful benefits. Many investors see Treasury Bonds as a reliable base for a strong financial portfolio. These assets offer stability that volatile markets often cannot match.
Safety and Security
These securities are investment grade bonds backed by the full faith and credit of the United States government. The government can tax and print currency, so default risk is virtually non-existent. They suit investors who want to protect their principal from market swings.
The safest investment is one that is backed by the stability of the nation itself, ensuring that your capital remains secure regardless of economic conditions.
Predictable Income
These bonds provide steady cash flow through fixed interest payments. You receive a set coupon payment every six months until the bond reaches maturity. This predictable income helps you plan future expenses because payment amounts and dates are known.
Tax Advantages
Besides safety and income, these assets offer significant federal tax exemption benefits. You must report interest income on federal tax returns, but state and local income taxes do not apply. This benefit can raise your net yield compared with other investment grade bonds without this status.
| Feature | Treasury Bonds | Corporate Bonds |
|---|---|---|
| Default Risk | Extremely Low | Moderate to High |
| Federal Tax | Taxable | Taxable |
| State/Local Tax | Exempt | Taxable |
| Income Source | Fixed Coupon | Fixed/Variable |
Using the federal tax exemption lets you keep more earnings. Adding Treasury Bonds to your strategy can support long-term wealth management. Understanding these core benefits is a first step toward your financial goals.
Risks Associated with Treasury Bonds
Navigating the bond market requires a clear view of possible financial risks. Government securities may seem safe, but no investment avoids every challenge. By understanding bonds, you can prepare your portfolio for changing economic conditions.
Interest Rate Risk
The most common challenge investors face is interest rate risk. When market interest rates rise, existing bond prices usually fall because newer bonds offer higher yields. If you sell before maturity, you might receive less than your original investment.
However, holding your bond until maturity means receiving its full face value despite market changes. This difference matters to investors who value capital preservation over short-term trading.
Inflation Risk
Another factor is inflation risk, which occurs when rising costs outpace your fixed interest payments. If inflation stays high, your future income may lose purchasing power over time. Long-term investors often worry when fixed income covers living expenses.
“Risk comes from not knowing what you are doing.”
Credit Risk
Although credit risk often involves corporate debt, it applies to every issuer. For United States government debt, this risk is extremely low. The Treasury can tax and print currency to meet its obligations, making it the global financial system’s gold standard.
| Risk Type | Primary Impact | Mitigation Strategy |
|---|---|---|
| Interest Rate Risk | Price volatility | Hold until maturity |
| Inflation Risk | Reduced purchasing power | Diversify asset classes |
| Credit Risk | Default possibility | Rely on government backing |
How to Purchase Treasury Bonds
We will guide you through the key steps for buying your first set of US Treasury securities. New investors and those seeking variety can use clear government-approved ways to join these stable markets.
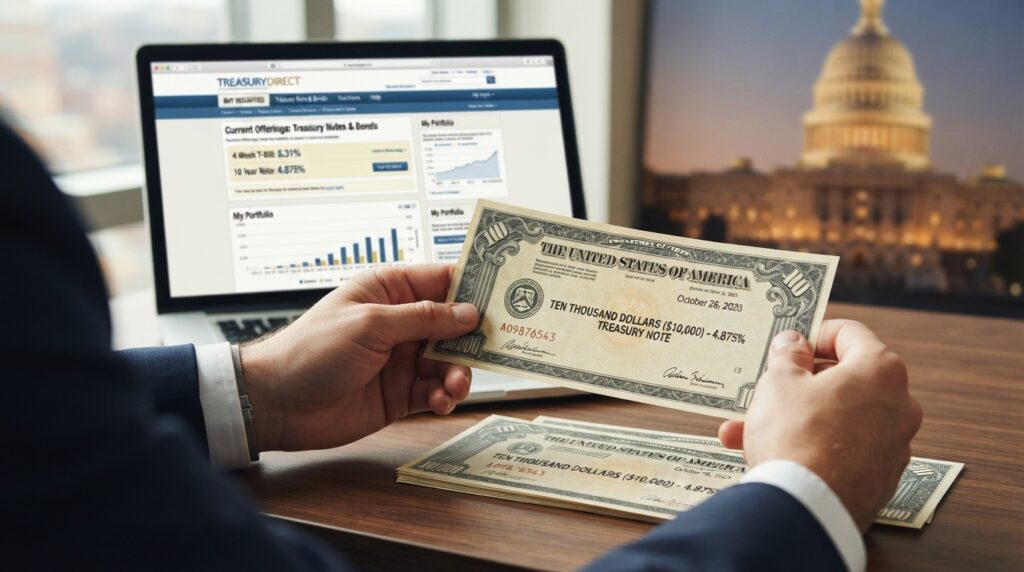
Direct Purchase through TreasuryDirect
The most common way to buy these assets is through the official TreasuryDirect website. This platform lets you open an account and buy securities directly from the government without middleman fees.
After your account is verified, you can link your bank account to fund purchases. This secure, paperless system makes managing government debt holdings simple and efficient.
Buying through a Broker
Many investors use a traditional brokerage firm for their financial needs. A broker lets you view your US Treasury securities beside stocks and mutual funds on one dashboard.
Some brokers charge transaction fees, but they often offer stronger customer support and research tools. This method suits investors who want their entire portfolio in one place.
Auction Process Explained
Understanding the Treasury auction is vital for serious investors. When you buy new issues, the government sets the interest rate according to market demand.
“The beauty of the auction system lies in its transparency, ensuring that every participant has a fair chance to secure their desired yield.”
You can submit a noncompetitive bid, which guarantees the auction will give you the security at its determined yield. A competitive bid lets you name the exact yield you will accept. However, your bid may not be filled if that yield is too high.
| Feature | TreasuryDirect | Brokerage Firm |
|---|---|---|
| Account Fees | None | Varies by firm |
| Ease of Use | High | Very High |
| Bid Type | Noncompetitive bid | Competitive/Noncompetitive |
| Treasury auction | Direct access | Via broker interface |
After the auction closes, settlement begins. Your account is charged, and the securities are registered electronically in your name. This step completes your entry into government-backed investing.
Understanding the Terms of Treasury Bonds
To make smart investment choices, we must learn the bond market’s basic terms. Understanding fixed-income securities helps us compare options with confidence.
Maturity Periods
The maturity date is the day the government repays the original loan. It marks the end of the bond’s life. At that time, the investor receives the full principal, and interest payments stop.
Face Value and Coupon Rates
Every bond has a face value, the amount the government promises to pay at maturity. This amount is also called the par value. The bond also pays a coupon rate, its fixed annual interest rate.
“An investment in knowledge pays the best interest.”
These terms work together to provide steady income. The table below summarizes their relationship:
| Term | Definition | Impact |
|---|---|---|
| Face Value | Principal amount | Determines final payout |
| Coupon Rate | Annual interest | Sets regular income |
| Maturity Date | End of term | Signals return of capital |
Yield Explained
Although the coupon rate stays fixed, the actual yield can change with the bond’s market price. Buying below face value increases our effective return. Buying at a premium lowers the total percentage return.
This relationship matters to every investor. It shows why existing bond prices move opposite interest rates. Tracking these measures helps us judge our holdings’ true value over time.
Treasury Bonds vs. Other Investments
To build a balanced financial future, we must compare the stability of government bonds with other popular choices. Each asset class has its own risk and reward profile, which can affect our portfolio’s performance. Knowing these differences helps us choose options that match our personal financial goals.
Comparison with Stocks
Stocks represent ownership in a company and often offer more growth than fixed-income securities. This chance for gain also brings market volatility and possible short-term losses. In contrast, investment grade bonds like Treasuries offer predictable income and can cushion turbulent market cycles.
Comparison with Corporate Bonds
Treasuries have the full faith and credit of the U.S. government, while corporate bonds come from private companies. These companies face greater default risk, so they usually offer higher yields to attract investors. We often see corporate bonds as a middle ground between government debt safety and the higher risk of equities.
Real Estate Considerations
Many investors choose real estate investments for passive income and protection against inflation. Unlike bonds, property ownership requires active management, maintenance, and significant upfront capital. Real estate is also less liquid than Treasury securities, so converting property to cash may take months when we need funds.
| Asset Class | Risk Level | Primary Benefit | Liquidity |
|---|---|---|---|
| Treasury Bonds | Very Low | Safety & Income | High |
| Corporate Bonds | Moderate | Higher Yield | Moderate |
| Stocks | High | Capital Growth | High |
| Real Estate | Moderate/High | Tangible Asset | Low |
How to Calculate Returns on Treasury Bonds
We can measure the actual profit from our Treasury holdings with several key formulas. These measures help us compare assets and match our portfolio to long-term financial goals.
Interest Payments Calculation
The simplest bond income comes from interest payments, also called coupon payments. Bonds typically pay them twice yearly, based on the coupon rate and face value.
Multiply the bond’s face value by its coupon rate to calculate annual income. For example, a $1,000 bond with a 3% coupon rate pays $30 yearly. This income comes as two $15 payments.
Yield to Maturity Explained
The yield to maturity (YTM) gives a fuller measure than the coupon rate. It estimates total return when we hold the security until its maturity date.
YTM considers the current market price, face value, and time left before the bond expires. It shows the expected annual percentage return when all payments arrive on time.
“The beauty of the yield to maturity calculation is that it captures the full picture of your investment’s potential, factoring in both the income stream and the eventual return of principal.”
Total Return Considerations
The total return may differ from YTM if we sell before the maturity date. If market interest rates fall, our bond’s price may rise, creating a capital gain.
If rates rise, our bond’s market price may fall, causing a capital loss when we sell early. Thus, the total return includes interest payments and changes in the bond’s market value.
| Metric | What It Measures | Key Factor |
|---|---|---|
| Coupon Rate | Annual cash flow | Face Value |
| Current Yield | Income relative to price | Market Price |
| Yield to Maturity | Total annualized return | Time to Maturity |
Selling Treasury Bonds
You are not locked into your investment forever. The secondary market lets investors sell assets when life changes or goals shift. Many investors hold securities until the final maturity date, but understanding the bond market helps them sell sooner.
Options for Selling
Most individual investors manage sales through a brokerage account. When you sell, your broker connects you with buyers in the secondary market. This process is efficient and allows quick execution during standard trading hours.
It is important to remember that you need not hold securities until the maturity date. A brokerage platform lets you list your holdings for sale at any time. The broker handles the trade and records the ownership transfer correctly.
Market Prices and Timing
When you sell before the term ends, you receive the current market value, not the original face value. Supply and demand set this price, and they can change daily. Know the bid-ask spread, which shows the gap between buyer offers and seller requests.
Timing your sale can strongly affect your final proceeds. During high liquidity, you may receive a price near the current fair market value. Low-volume periods may create a wider spread and reduce your total return.
Impact of Interest Rates
The key factor affecting Treasury Bond prices is the movement of prevailing interest rates. These variables have an inverse relationship; when market rates rise, existing bonds typically lose value. Newer bonds offer higher yields, making older, lower-yielding bonds less attractive to buyers.
If market interest rates decline, existing bonds may become more valuable. You could sell your holdings for a capital gain if you exit at the right time. The following table shows how these factors interact during the life of an investment.
| Scenario | Market Rate Trend | Impact on Price | Action Result |
|---|---|---|---|
| Rising Rates | Increase | Decrease | Potential Loss |
| Stable Rates | Neutral | Minimal Change | Par Value |
| Falling Rates | Decrease | Increase | Potential Gain |
Treasury Bonds and Economic Indicators
Treasury bonds offer a useful measure of the United States economy. They show how investors view future growth and stability. These securities respond to changing economic conditions.
Relationship with Inflation
When inflation rises, fixed bond payments lose purchasing power. Investors usually demand higher yields to offset that loss over time. As a result, bond prices often fall when persistent price increases seem likely.
Impact on Interest Rates
The federal funds rate, set by the Federal Reserve, strongly affects short-term Treasury yields. When the central bank changes this rate, effects spread through the financial system. We track the yield curve to compare long-term borrowing costs with short-term expectations.
Role in the National Debt
Selling Treasury securities is the government’s main way to fund the national debt. These bonds help the U.S. Treasury meet its fiscal duties and offer investors a safe haven. This steady debt supply supports global financial liquidity.
| Economic Indicator | Impact on Bond Prices | Investor Sentiment |
|---|---|---|
| Rising Inflation | Decreases | Cautious |
| Higher Federal Funds Rate | Decreases | Defensive |
| Increased National Debt | Variable | Watchful |
| Steep Yield Curve | Increases | Optimistic |
Understanding these forces helps us make informed decisions in the bond market. Tracking the yield curve as the federal funds rate changes can help us anticipate market trends. The link between government borrowing and economic health remains central to modern finance.
Current Trends in Treasury Bond Market
Today’s financial climate helps explain how Treasury yields move in real time. Market conditions change, and no forecast guarantees future performance. Broad economic signals help us understand forces shaping investments.
Recent Changes in Interest Rates
The bond market reacts to monetary policy and wider economic data. Federal Reserve decisions on inflation and employment shape interest rate trends. These changes affect prices for new and existing securities.
When rates rise, older bonds usually lose value to stay competitive. When rates fall, older bonds with higher coupons attract more investors. Tracking these changes helps manage return expectations.
Demand and Supply Factors
Federal budgets and national operations determine the supply of government debt. At government auctions, investor demand sets security prices. High demand often lowers yields, while low demand may require higher rates to attract buyers.
We monitor auction results as a key sign of market health. Institutional investors, such as pension funds and foreign central banks, help absorb this supply. Their participation shows the current appetite for risk.
Market Predictions
Analysts often study the yield curve to predict future economic activity. A normal curve slopes upward and reflects expected growth. An inverted curve may signal concern about a slowdown.
The yield curve is one of many indicators used to assess the future. Because the bond market reacts to unexpected news, we recommend checking official government data before final decisions. Tracking interest rate trends can build confidence when navigating financial markets.
Resources for Further Learning
Building a strong portfolio takes regular study and reliable data. Explore US Treasury bonds through trusted platforms to improve your strategy. Current information helps you handle market shifts with confidence.
Official Government Portals
TreasuryDirect remains the main source for security information. It offers auction schedules, tax forms, and maturity procedures. Use its secure interface to manage holdings and research specific savings bonds.
Educational References
Specialized investment guides can explain complex fiscal policies. They often show how to use Treasury auction resources for better decisions. Regular study helps you understand duration and yield.
Market Analysis Outlets
Reliable financial news outlets provide daily updates on interest rates and economic indicators. These reports help you adjust your approach to current market conditions. Check them regularly to track changes in the national debt landscape.