The United States government manages over $20 trillion in debt. This creates one of the safest investment landscapes on the planet. For many, Treasury Bills, or short-term government securities, offer entry into this financial system, capital protection, and predictable returns.
Unlike long-term bonds, these instruments mature from four weeks to one year. This schedule helps us match cash flow needs with specific financial goals. We will explore discount pricing, the impact of federal taxes, and the best strategies for maximizing profit.
Whether you are a conservative saver or tactical investor, understanding Treasury Bills is vital. We invite you to learn how to match these holdings with your personal risk tolerance and time horizon.
Key Takeaways
- These assets provide a high level of security for your principal investment.
- Maturity dates range from four weeks to one year, offering great flexibility.
- Investors purchase these at a discount to their face value.
- Interest earned is exempt from state and local income taxes.
- They are ideal tools for balancing risk within a diversified portfolio.
What Are Treasury Bills?
Treasury Bills are a basic part of many careful investment portfolios in the United States. These tools are short-term loans to the federal government for cash flow and public operations.
Overview of Treasury Bills
When we invest in Treasury Bills, we lend money to the government for a set, short period. Unlike traditional investments, they do not pay interest on a schedule. Instead, we buy them below face value, and the government pays the full amount at maturity.
The difference between the purchase price and face value is our profit. This makes T-bills popular for people seeking steady returns without stock market volatility.
Key Characteristics of T-Bills
One main feature is their short maturity schedule. The government offers T-bills with terms of four, eight, 13, 17, 26, and 52 weeks. This range lets us match our investment timeline to our financial needs.
Because the U.S. government fully backs them, many people consider them among the safest investments available. They offer strong liquidity, so we can access our funds if our needs change before maturity.
Difference Between T-Bills and Other Securities
It is important to distinguish these short-term tools from longer-term government debt. While US Treasury bonds and notes also have government backing, they differ in interest payments and time lengths.
You can learn more about these assets by reviewing this guide on Treasury bills vs bonds to see which fits your strategy. Unlike US Treasury bonds, which usually pay interest every six months, T-bills make no coupon payments. They are short-term debt, while other securities may hold your money for years or decades.
The Benefits of Investing in Treasury Bills
Treasury bills often anchor conservative investment strategies. They help us manage cash while pursuing clear financial goals. Their advantages explain why many financial market participants choose them.
Safety and Security
These assets are backed by the United States government. This guarantee ensures repayment of the principal at maturity. Therefore, many investors call them risk-free investments when held until their term ends.
This protection mainly guards against default. Although they are among the safest fixed-income securities available, market forces can still affect them. For investors focused on preserving capital, Treasury security is hard to match.
Liquidity Advantages
Liquidity is another major benefit when we manage our portfolios. Treasury bills can quickly become cash when our financial needs change. This flexibility helps us maintain an emergency fund or prepare for short-term expenses.
- High Marketability: There is a deep and active secondary market for these bills.
- Quick Settlement: Transactions typically settle in a very short timeframe.
- Accessibility: We can easily sell our holdings through brokers or financial institutions.
Diversification for Your Portfolio
Adding these bills to a broader strategy can balance our overall risk. Holding stocks, cash, and fixed-income securities can reduce volatility in equity markets. This mix provides a steady base while we pursue growth elsewhere.
These risk-free investments may offer lower returns than volatile assets, but they still support a balanced portfolio. They provide a reliable anchor during economic uncertainty. We see them as a smart way to protect wealth while keeping options open.
How Treasury Bills Work
The process behind T-bills is simple and efficient for the average investor. Unlike traditional bonds, they do not pay interest at regular times. Their pricing structure helps investors manage short-term money.
Maturity Periods Explained
When you buy these government securities, you choose a term that fits your cash needs. The government offers T-bills with terms from four weeks to 52 weeks. This choice helps match your investment period with financial goals or upcoming expenses.
Four-week and eight-week bills suit investors who need to park cash temporarily. A 52-week bill offers a slightly longer commitment but remains a safe, government-backed asset.
How Interest is Earned
Investors do not receive regular coupon payments with these instruments. Instead, they sell at a discount rate, so you pay less than the bill’s face value. At maturity, the difference between your price and the full face value is your total interest.
For example, you might buy a bill with a face value of $1,000 for $990. You earn $10 at maturity, and this simple yet effective method locks in your return when you buy.
Auction Process for T-Bills
The government issues these securities through a structured Treasury auction process. Institutional and individual investors submit requests to buy debt during these events. Most individual investors choose a noncompetitive bid, which guarantees they receive the security at the yield set by auction results.
A noncompetitive bid means you do not need to name a target rate. Large institutions often use competitive bids to influence the final discount rate. These auctions follow a regular schedule, so investors have frequent chances to participate.
Who Can Invest in Treasury Bills?
We often receive questions about who may enter the market for government debt instruments. The U.S. Treasury makes these securities available to many participants, from everyday savers to large financial organizations.
Individual Investors
For most people, the main way to invest is through the TreasuryDirect website. To meet TreasuryDirect eligibility requirements, you must live in the U.S. and have a valid Social Security number. You also need a U.S. address and a linked bank account.
Individual investors usually use noncompetitive bidding. You accept the yield set at the auction instead of choosing a specific rate. It is a straightforward way to secure your capital in government debt instruments without needing advanced trading expertise.
Institutional Investors
Large entities, such as pension funds, insurance companies, and banks, use the market differently. These institutional investors often use competitive bidding, which lets them name the exact yield they will accept.
These organizations manage vast sums, so their participation supports market liquidity. By placing large orders, institutional investors help the government fund its operations efficiently and support the wider financial system.
Foreign Entities
People outside the United States may also buy these securities. They often work through international brokerage firms or specialized custodial banks. These entities must follow tax reporting rules and account regulations that differ from domestic requirements.
We recommend that foreign investors consult a financial advisor about the custodial implications of holding U.S. debt. The process is more complex than for domestic residents. However, it remains a viable strategy for investors seeking to diversify their holdings with high-quality assets.
How to Purchase Treasury Bills
You have several reliable ways to buy Treasury Bills for your portfolio. Each method suits different needs, from hands-on management to automated convenience. Choosing the right platform helps build a secure financial foundation.
Through a Broker
Many investors use a brokerage account to keep their financial assets in one place. Through a broker, you can access new issues and the secondary market. This flexibility lets you sell before maturity if your liquidity needs change.
Brokers often offer simple interfaces that make bidding easier. However, check whether your firm charges transaction fees for these purchases. Verify minimum investment requirements before starting a trade.
Directly from the Treasury
If you want to avoid intermediary fees, buy securities directly through TreasuryDirect. This government-run website lets you join new-issue auctions without commissions. It suits long-term investors who plan to hold assets until maturity.
The platform serves individual investors seeking a direct relationship with the government. Although its interface is strictly functional, it securely manages your holdings. You can also schedule recurring purchases to build your position over time.
Online Platforms and Services
For a more passive approach, a Treasury bill ETF offers a convenient alternative to individual securities. These funds trade like stocks and provide high liquidity with professional management. They may charge small expense ratios, but they remove individual maturity dates from your tasks.
Some modern financial services offer managed accounts with auto-roll functionality. This feature reinvests your principal in new bills when current bills mature. Use the comparison below to find the method that best matches your investment style:
| Method | Best For | Primary Benefit | Cost Structure |
|---|---|---|---|
| Brokerage Account | Active Traders | Secondary Market Access | Varies by Firm |
| TreasuryDirect | Buy-and-Hold | No Commissions | Free |
| Treasury Bill ETF | Passive Investors | High Liquidity | Expense Ratio |
Understanding the Risks
Treasury bills often seem like a safe harbor, but they still carry financial hazards. Every investor should know that government-backed securities carry specific challenges. Knowing these risks helps us set expectations and build a stronger financial plan.
Market Risks
The bond market can fluctuate and affect your holdings’ value if you sell before maturity. Although T-bills are stable, market risk appears when you must sell during unfavorable pricing. Holding your bills until maturity avoids this volatility.
Interest Rate Risks
There is an inverse relationship between current interest rates and existing security prices. When market rates rise, older bills with lower yields usually lose value. This interest rate risk matters if you need cash before the scheduled maturity date.
These price changes affect only investors who sell early. If you hold the investment to the term’s end, you receive the full face value despite market shifts. This strategy limits changing rates’ effect on your principal.
Inflation Risks
One subtle threat to any fixed-income portfolio is inflation risk. This happens when inflation rises faster than your Treasury bills’ yield. Over time, it can reduce purchasing power, so your money buys fewer goods and services.
T-bills preserve capital well, but they may not grow much beyond inflation. We suggest balancing your portfolio to protect long-term goals from rising costs. By staying informed about the bond market, we can make better asset-allocation decisions.
Tax Implications of Treasury Bills
When we assess investment profits, we must consider how the government taxes our earnings. Understanding the tax landscape is a critical step in maximizing our capital’s growth over time.
Federal Tax Considerations
Remember that Treasury Bills face federal income tax. The government treats their earnings as ordinary interest income for tax purposes.
You must report your gains on your annual federal tax return. Since your federal tax rate may depend on total income, estimate your after-tax yield first.
State and Local Tax Benefits
A key benefit is the state and local tax exemption. When you hold these bills directly, the interest you earn is generally free from state and local income taxes.
This benefit often makes these securities more competitive than other taxable bonds. Avoiding these extra taxes may help you keep more earnings and increase your net return.
Reporting Interest Income
Investment vehicles do not all receive the same tax treatment. If you invest in Treasury Bills through a mutual fund or an exchange-traded fund, the fund may not qualify for the same state and local tax exemption.
Keep accurate transaction records throughout the year. We strongly encourage you to consult a qualified tax professional to report your interest income correctly for your financial situation.
Strategies for Investing in Treasury Bills
A structured Treasury bill plan can help manage cash. Treating these securities as money market investments aligns liquid assets with financial timelines.
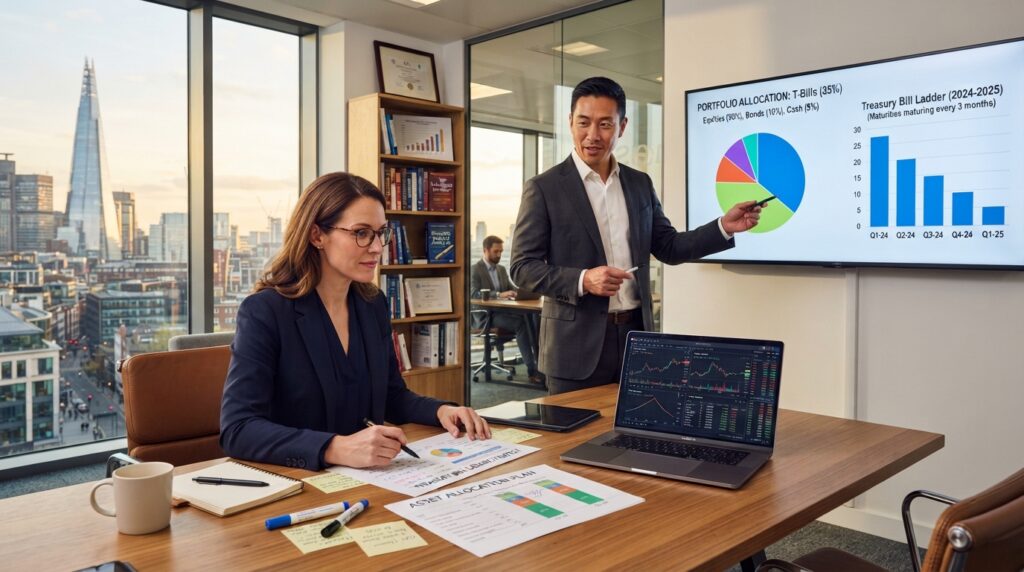
Short-Term vs. Long-Term Investments
Choosing maturity dates is a key step in short-term investing. If you need cash for an upcoming tax payment or home repair, choose a four-week or eight-week bill.
If you want to lock in rates longer, you might choose 52-week bills. This choice can shield your capital from immediate market changes and may secure a higher yield over the year.
Laddering Strategy
A Treasury bill ladder uses bills with staggered maturity dates. Spreading investments across timeframes makes part of your capital available at regular intervals.
“The secret to successful investing is not to avoid risk, but to manage it through diversification and patience.”
This method provides steady liquidity without requiring guesses about interest rates. When each bill matures, you can reinvest the proceeds in a new long-term bill or keep the cash if your needs change.
Combining T-Bills with Other Investments
Effective portfolio allocation considers how T-bills work with other asset classes. T-bills can provide a stable base that balances volatile holdings, such as equities or long-term corporate bonds.
| Asset Class | Primary Role | Risk Level |
|---|---|---|
| Treasury Bills | Liquidity & Safety | Very Low |
| Equities | Growth Potential | High |
| Corporate Bonds | Income Generation | Moderate |
Adding T-bills to certificates of deposit or cash reserves creates a strong safety net. This diversified approach helps keep your financial plan resilient during broad economic shifts.
Tracking Your Investments in Treasury Bills
Careful oversight of Treasury bills helps keep your capital productive. Treating these instruments as core financial assets helps align holdings with changing economic conditions and personal goals.
Monitoring Treasury Rates
Tracking current Treasury rates is a basic task for every investor. We regularly check official auction results and compare those yields with our existing portfolio.
Maintain a simple tracking log with these details for every bill we hold:
- Specific maturity dates to avoid missed reinvestment windows.
- The original purchase price and the face value at maturity.
- The current market yield compared to the initial discount rate.
Evaluating Performance
When we assess investment performance, we must separate annualized yield from actual dollar income. Yield shows growth as a percentage, while the dollar amount shows cash added to our accounts.
Investors who hold Treasury bill ETFs must also consider expense ratios. These fees may lower net returns over time, so we compare fund performance with the underlying index to check efficiency.
Reinvesting Earnings
Many investors use the auto-roll feature to simplify reinvestment after bills mature. This tool uses the principal from a maturing bill to purchase another, keeping our money working without manual action.
However, we still review our strategy to ensure automatic reinvestment matches our current financial needs. Even with automated systems, portfolio attention helps us respond to changing interest rates or personal liquidity needs.
Conclusion: Is Investing in Treasury Bills Right for You?
Choosing the right path for our money requires a clear look at our personal needs. We must weigh the safety of the U.S. government against our desire for growth.
Aligning with Personal Objectives
Treasury Bills serve as a cornerstone of conservative investing. These assets offer a predictable path toward our financial goals. By holding them until maturity, we receive the full face value of our initial commitment.
Refining Our Investment Approach
We should view T-bill investments as a way to add stability to our broader holdings. These instruments offer lower yields than volatile stocks, but they protect our capital from market swings. Evaluate your tax situation and inflation expectations before committing funds.
A balanced strategy helps our money work hard while keeping our risk profile low.