Nearly 40% of long-term wealth preservation often comes from stable, non-equity assets. Many investors focus on stocks, but fixed income acts as a quiet engine during turbulent times.
These assets usually pay regular interest or dividends. They create a steadier cash-flow stream for your household. Adding them can help manage risk and balance exposure to market swings.
This guide shows how these tools can work with your existing stocks. They offer stability but still face risks, including inflation and interest-rate shifts. You can put volatility to work with strategic fixed income investments for stronger long-term results.
Key Takeaways
- Assets provide a reliable cash-flow stream through regular interest payments.
- Diversification helps mitigate the impact of stock market volatility.
- Effective risk management requires balancing rate sensitivity with credit quality.
- Investors must remain mindful of inflation and issuer-related risks.
- A balanced approach allows for better long-term wealth preservation.
Understanding Fixed Income: An Overview
When building wealth, fixed income investments often act as a reliable engine for our financial goals. These assets provide predictable income through scheduled interest or dividend payments. They also aim to return the original principal when the stated term ends.
Definition and Key Features
At its core, fixed income means an investment where a borrower or issuer must make scheduled, fixed payments. These payments usually cover interest for lending capital over a specific period. Unlike stocks, these instruments represent investor loans rather than ownership.
These assets offer capital preservation and steady cash flow. Market changes can affect security prices, but contracts make payments clearer than in equity markets. Investors often use them to balance risk in aggressive growth portfolios.
Types of Fixed Income Securities
Many bonds and other instruments are available, with different levels of risk and reward. Treasury securities come from the federal government and rank among the safest options. They are backed by the full faith and credit of the United States. In contrast, corporate bonds come from companies funding operations, so they usually carry higher risk and potential yields.
Municipal bonds come from states, cities, or counties funding public projects. They often provide tax advantages for specific financial situations. Beyond traditional debt, certificates of deposit and fixed annuities offer different maturity and income structures.
| Security Type | Issuer | Risk Level | Primary Benefit |
|---|---|---|---|
| Treasury Securities | Federal Government | Very Low | High Safety |
| Corporate Bonds | Private Corporations | Moderate to High | Higher Yields |
| Municipal Bonds | Local Governments | Low to Moderate | Tax Advantages |
| Certificates of Deposit | Banks | Very Low | FDIC Insurance |
The Role of Fixed Income in Investment Strategies
Building a resilient financial future takes more than choosing high-growth stocks. We find that fixed income investments provide a vital counterweight to volatile equity markets.
These assets can create a smoother path for our capital over time. They balance stocks’ aggressive nature with steady, predictable cash flows from debt securities.
Diversification Benefits
True diversification means more than owning different companies. We spread exposure across asset classes, issuers, and maturity dates to reduce concentration risks.
Treating all bonds as interchangeable is a common mistake that can hurt performance. Instead, we choose government and corporate debt to keep our portfolio strong through market cycles.
“Diversification is the only free lunch in investing.”
Stability and Risk Management
We aim to preserve capital and lower overall portfolio volatility. Although no investment is risk-free, fixed income can steady portfolios during turbulent economic periods.
We must watch credit risk, especially when seeking higher yields from issuers with weaker finances. We balance potential income against the chance of default as part of risk management.
Ultimately, bonds provide a needed anchor for our holdings. By managing our exposure to credit risk, we can seek consistent returns within a disciplined investment framework.
How Fixed Income Yields Work
The price you pay for a bond and its income show a basic finance relationship. When we study bonds, we must look beyond face value to measure possible earnings. These ideas help us understand the complexities of fixed income markets.
Coupon Payments Explained
A coupon payment is the yearly interest a bond pays, shown as a percentage of face value. Issuers set this rate when they issue the security, and it usually stays fixed. We receive these payments at regular times, creating a predictable cash flow.
The coupon rate stays the same even when the bond’s market price changes. If you hold the security until maturity, you keep collecting payments as scheduled. This stability makes these assets useful in many investors’ long-term plans.
Yield vs. Total Return
While the coupon rate gives a starting point, bond yields show your actual return more clearly. Yield measures investment income, but it may not include market price changes. Total return includes price growth, reinvested income, and original coupon payments.
Investors should know that interest rate risk strongly affects these calculations. When market rates rise, existing bond prices usually fall. This can lower total return if you sell before maturity. A higher quoted yield often means the market is paying you for this added risk.
| Yield Metric | Definition | Key Insight |
|---|---|---|
| Coupon Rate | Fixed interest payment | Based on face value |
| Current Yield | Annual income / Price | Reflects market price |
| Yield to Maturity | Total expected return | Assumes holding to end |
Understanding these distinctions helps us make better portfolio decisions. We must balance income goals with market volatility to manage risk. Always ask whether a yield fits your financial goals and tolerance for market shifts.
The Impact of Interest Rates on Fixed Income
Interest rates drive the performance of your bond holdings. When you invest in Fixed Income, your capital responds to broader economic shifts. These changes often shape your total return during the investment period.
Understanding the Inverse Relationship
The bond market follows a basic rule: interest rates and bond prices move in opposite directions. When market rates rise, existing bond prices typically fall. New bonds offer higher coupons, so older, lower-yielding bonds become less attractive.
Duration strongly affects how much a bond’s price moves. Bonds with longer maturities usually react more to rate changes than shorter-term bonds. This sensitivity creates a key part of interest rate risk that investors should monitor.
| Factor | Rising Rates | Falling Rates |
|---|---|---|
| Bond Prices | Decrease | Increase |
| New Bond Yields | Higher | Lower |
| Investor Strategy | Shorten Duration | Lengthen Duration |
Making Sense of Rate Changes
Federal Reserve policy decisions strongly influence bond market trends. When the central bank changes the federal funds rate, effects spread across the economy. These effects reach corporate debt and government securities.
We suggest avoiding portfolio decisions based only on short-term forecasts.
Instead, build a resilient strategy through maturity diversification. With a laddering approach, you can spread investments across various maturity dates. This method helps reduce interest rate risk and capture competitive bond yields over time.
Discipline helps you navigate changing bond market trends without reacting to daily volatility in Fixed Income markets.
Choosing the Right Fixed Income Investments
We should assess debt instruments carefully to build a strong portfolio that earns income. A clear framework should consider issuer strength, maturity, and your financial goals. Knowing how debt markets differ helps us match holdings with long-term goals.
Government vs. Corporate Bonds
In this market, treasury securities are often the foundation of a stable portfolio. These government-backed bonds have little default risk, making them useful for protecting capital. Companies issue corporate bonds to fund operations or expansion, and these bonds may offer higher returns for added risk.
We should also consider municipal bonds from states, cities, or counties. They often provide tax-free income, which can benefit investors in certain tax brackets. A mix of these choices spreads exposure across sectors and may reduce portfolio volatility.
Assessing Credit Risk
Assessing credit risk is essential before investing in any debt instrument. We must review whether issuers can pay interest and repay principal at maturity. Higher bond yields often signal that markets see a greater default risk.
Good analysis looks beyond the surface. We should review these factors before choosing investments:
- Issuer Strength: Reviewing credit ratings from agencies like Moody’s or S&P.
- Liquidity: Ensuring we can sell our bonds without significant price impact.
- Call Provisions: Checking if the issuer can redeem the debt early, which affects bond yields.
Ultimately, we need a diversified approach to limit losses from one issuer’s financial trouble. We can then balance risk and reward to build a portfolio with stable, steady income.
Tax Considerations for Fixed Income Investors
Managing your tax liability is a key part of your fixed income strategy. Interest payments provide steady cash, but your final amount depends on your holdings. Knowing these differences helps you make informed choices and protect your bottom line.
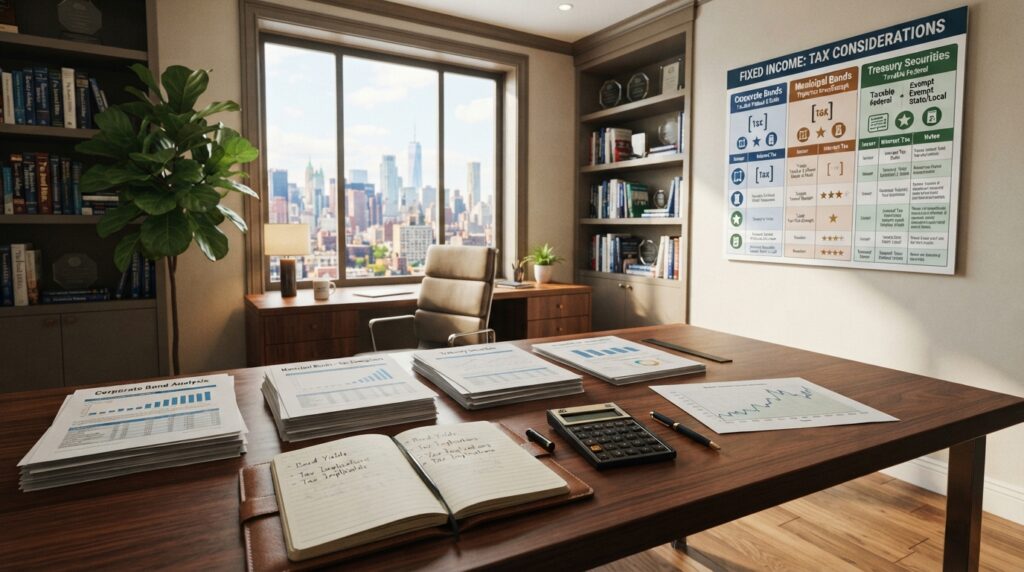
Taxable vs. Tax-Exempt Bonds
Tax treatment varies greatly by issuer. Interest from corporate bonds is usually ordinary income and subject to federal and state taxes. Interest from municipal bonds is typically exempt from federal income tax and sometimes state and local taxes too.
Treasury securities occupy a middle place in the tax system. They face federal income tax but are exempt from state and local taxes. This structure makes them popular with investors in high-tax areas.
“The art of investing is not just about what you earn, but what you keep after the tax man takes his share.”
| Investment Type | Federal Tax | State/Local Tax |
|---|---|---|
| Corporate Bonds | Yes | Yes |
| Municipal Bonds | No | Often No |
| Treasury Securities | Yes | No |
Capital Gains Tax Implications
You must also consider possible capital gains, not just interest income. If you sell a bond above its adjusted cost basis, the profit is usually a capital gain. The tax rate depends on how long you held the asset.
Keep the following points in mind when planning your taxes:
- Adjusted Cost Basis: Always track your purchase price and any adjustments to ensure accurate reporting.
- Holding Periods: Short-term gains are often taxed at higher ordinary income rates compared to long-term capital gains.
- Professional Guidance: Tax laws are complex and subject to change, so we strongly recommend consulting with a qualified tax professional to confirm your specific obligations.
Reviewing tax status of your corporate bonds, municipal bonds, and treasury securities helps align your portfolio with financial goals. Proactive tax planning helps maximize your net returns over the long term.
How to Integrate Fixed Income into Your Portfolio
We can improve investment results by adding fixed income to our broader financial plan. Our choices should match our time horizons, liquidity needs, and comfort with market swings.
A balanced plan can protect our capital from inflation while supporting market growth. We should treat these assets as tools for stability, not passive holdings.
Asset Allocation Recommendations
When setting our target allocation, we can use specific strategies to manage our exposure. These methods help us handle changing markets and meet long-term goals.
- Bond laddering: We purchase bonds with staggered maturity dates to create steady cash flow and reinvestment opportunities.
- Barbell approach: We hold short-term and long-term securities to seek yield while keeping liquidity.
- Bond tents: We may increase fixed income investments near retirement to reduce sequence-of-returns risk.
Timing Your Investments
Market timing is hard, but we can manage entry points by watching interest rate risk. When rates rise, existing holdings often lose market value. So, we should spread purchases over time.
We should not try to time the market perfectly. Instead, steady contributions can reduce the impact of changing yields on our bonds.
fixed income should work with growth assets. Keeping some money in equities helps protect long-term purchasing power from inflation. Managing interest rate risk helps us stay on course during short-term economic shifts.
Common Misconceptions About Fixed Income
Finance includes myths that can cloud our judgment. People often hold firm views about how assets should work in a portfolio. Separating fact from fiction helps us make informed financial choices.
Fixed Income is Only for Conservative Investors
A common mistake is thinking that Fixed Income is only for people nearing retirement. These assets can add stability, but they also serve other purposes. Aggressive investors often use them to manage liquidity or hedge against volatility in equity markets.
Strategic allocation supports balance at any risk level. For example, holding treasury bonds can provide a reliable source of cash flow that can be reinvested during market downturns. This flexibility makes fixed income investments useful in any long-term strategy.
Bonds are Always Safe Investments
Another risky assumption is that all bonds are completely safe. They usually fluctuate less than stocks, but market forces can still affect them. Investors should consider factors that may change their value over time.
These assets carry several risks:
- Interest Rate Risk: Prices often fall when market rates rise.
- Inflation Risk: Rising costs can erode the purchasing power of fixed payments.
- Credit Risk: The possibility that an issuer may fail to meet payment obligations.
- Liquidity Risk: Difficulty in selling an asset quickly without impacting its price.
This summary compares common myths with market reality:
| Common Myth | Market Reality |
|---|---|
| Only for retirees | Useful for all investors |
| Guaranteed safety | Subject to market risks |
| No growth potential | Essential for total return |
Ultimately, fixed income investments need active monitoring to match our goals. When we recognize that bonds carry specific risks, we can protect our capital and pursue broader financial goals.
Monitoring and Adjusting Your Fixed Income Holdings
Buying bonds is only the start of your investing journey. Regular reviews help keep your portfolio aligned with your financial goals.
Regular Portfolio Review Strategies
Review your holdings at least once a year. Check maturity dates, current yields, and the overall credit quality of your assets.
Some investors review their holdings quarterly or twice a year. This helps them track changing bond market trends. These checks show whether your strategy still provides the stability you need.
When to Rebalance
Rebalancing restores your portfolio’s original target allocation. Consider it when market performance or personal changes shift your asset mix.
Separate needed changes from emotional responses to short-term volatility. You may need to rebalance when interest rate risk or credit risk exceeds your comfort level.
Effective rebalancing helps preserve your target risk profile without unnecessary trading. Consistency is key to keeping your fixed income strategy a reliable part of your broader investment plan.
Conclusion: Maximizing Your Portfolio with Fixed Income
Building a resilient financial future starts with understanding how different assets work together. Adding Fixed Income to your strategy can balance your portfolio during market volatility.
Successful investors track current bond market trends and use them to make smart choices. These insights help us adjust holdings as economic conditions change. A proactive approach can protect capital while producing steady returns.
Review your long-term goals and risk tolerance today. Exploring different fixed income investments helps tailor a plan to your unique needs. A balanced approach remains a strong path toward lasting wealth.
Start by reviewing your current asset allocation. Contact a financial advisor at Vanguard or Fidelity to discuss how these tools fit your specific situation. Your path to a stronger portfolio starts with informed choices.