Did you know the United States government manages a debt market worth more than $20 trillion? For many investors, Treasury Bills offer a reliable way to join this massive financial market. These instruments support investors who seek stability during market swings.
Many investors seek short-term investments that protect their cash and provide peace of mind. They buy these government-backed securities at a discount and receive a predictable return at maturity. This structure makes them a leading risk-free asset for conservative portfolios.
Whether you save for a near-term goal or protect your capital, T-bills offer a clear path. They provide high liquidity and federal government backing, helping keep your principal secure. Let us explore how these tools can strengthen your financial strategy today.
Key Takeaways
- These securities are backed by the full faith and credit of the U.S. government.
- Investors purchase them at a discount and receive the full face value at maturity.
- They are highly liquid, allowing for easy conversion to cash when needed.
- These instruments serve as a primary choice for capital preservation.
- Maturity dates are short, typically ranging from a few days to one year.
What Are Treasury Bills?
Treasury Bills are a unique, short-term form of government debt. These fixed-income securities are issued by the U.S. Department of the Treasury to fund daily federal operations. Unlike longer-term government bonds, these securities help manage cash flow over short periods.
Definition and Overview
Treasury Bills, often called T-Bills, are debt obligations backed by the full faith and credit of the United States government. They differ from US Treasury notes, which usually mature in two to ten years. Because they mature within one year, Treasury Bills are highly liquid assets.
Investors buy these securities below their face value. Their profit equals the difference between the purchase price and the maturity payment. You can learn more about Treasury bill and treasury bond terms to see how maturity affects your strategy.
Key Features of Treasury Bills
The main appeal of these fixed-income securities is their safety and simplicity. They rank among the safest investments because they carry almost no default risk. Key features include short terms, low entry costs, government backing, and easy resale.
- Short Maturity: Terms range from four weeks to 52 weeks.
- Minimum Investment: You can start investing with as little as $100.
- Government Backing: They are fully guaranteed by the U.S. government.
- Secondary Market: Investors can sell them before maturity if they need immediate cash.
The table below compares Treasury Bills with other common debt instruments.
| Instrument | Maturity Range | Interest Payment |
|---|---|---|
| Treasury Bills | 4 to 52 Weeks | Sold at Discount |
| US Treasury Notes | 2 to 10 Years | Semi-annual Coupons |
| Government Bonds | 20 to 30 Years | Semi-annual Coupons |
How Treasury Bills Work
A T-bill begins its journey before reaching your portfolio. These securities help the federal government manage short-term cash needs. The government issues this debt to borrow public money for operating expenses.
Issuance Process
The U.S. Treasury sells these securities through a carefully structured system. When the government needs funds, it announces a new debt sale. Investors can buy through official government portals, banks, or brokerage firms.
You can hold these securities until their maturity date. Then, you receive the investment’s full face value. If your needs change, you can sell your holdings in financial markets before maturity.
Auction Mechanism
The system relies on Treasury auctions, which set the interest rates investors receive. Individual investors and large institutions can join these auctions. Participants usually choose between two main bidding methods.
With Noncompetitive bidding, you accept the auction’s yield, and your order is filled. With competitive bidding, you name the yield you will accept. If that yield is too high, the system may reject your bid.
This competition helps the government secure funding at the best available rates. Backed by the full faith and credit of the United States, T-bills remain a cornerstone of global financial markets. Taking part in Treasury auctions offers everyone a transparent way to invest in government debt.
Types of Treasury Bills
We group these securities by maturity dates to match financial goals with suitable instruments. Choosing the right duration is a critical step in portfolio management. It affects liquidity and how often you must reinvest.
These T-bills form the foundation of many conservative portfolios.
4-Week Treasury Bills
These securities have the shortest available maturity and suit immediate cash needs. Investors often use these as short-term investments to hold extra capital for one month. They offer a safe place while keeping funds available for upcoming expenses.
8-Week Treasury Bills
The eight-week option gives investors a slightly longer horizon when funds are not needed at once. It suits people bridging a two-month gap in their financial plans. It balances safety with a predictable return over a short period.
13-Week Treasury Bills
Often called the three-month bill, this security is a staple among money market instruments. Many investors use it to match quarterly financial cycles. It offers a stable yield while keeping capital fairly liquid for future opportunities.
26-Week and 52-Week Treasury Bills
For longer horizons, the six-month and one-year T-bills offer different planning benefits. These terms often provide higher yields than shorter bills because investors lock in capital longer. They are excellent tools for investors who want to secure a rate for a full year without the volatility of other market assets.
| Maturity | Primary Use | Liquidity Level |
|---|---|---|
| 4-Week | Immediate Cash | Very High |
| 13-Week | Quarterly Planning | High |
| 52-Week | Longer-term Yield | Moderate |
Benefits of Investing in Treasury Bills
When building a balanced portfolio, we often seek tools that provide stability and peace of mind. Treasury Bills can serve as a cornerstone for preserving capital while keeping money available. Reviewing the primary Treasury Bill benefits shows why individual and institutional investors value these securities.
Safety and Security
The main advantage of these securities is their status as a risk-free asset. The United States government backs them with its full faith and credit, so default is virtually non-existent. They suit investors who value protecting principal more than pursuing high-risk growth.
Liquidity and Accessibility
These money market instruments are highly liquid, so investors can turn them into cash quickly if needed. A robust secondary market lets investors sell bills before maturity without significant loss of value. Low minimum investment requirements make them accessible to small savers and large corporations.
Predictable Returns
One attractive feature of Treasury Bills is the certainty they offer: at maturity, we know the exact amount received. The return depends on the difference between the purchase price and face value. These instruments offer favorable tax treatment; interest is exempt from state and local income taxes, raising after-tax yield.
| Feature | Primary Benefit | Investor Impact |
|---|---|---|
| Government Backing | Default Risk Near Zero | High Capital Security |
| Secondary Market | High Liquidity | Easy Cash Access |
| Tax Status | State/Local Tax Exempt | Higher Net Returns |
| Maturity Structure | Fixed Payouts | Predictable Planning |
How to Buy Treasury Bills
Getting started with T-bills is simple and gives investors several flexible options. You can take a hands-off approach or manage your portfolio while adding these short-term investments to your financial plan.
Through a Broker
Many investors buy securities through a brokerage account for added convenience. Brokers let you manage your T-bills alongside stocks and mutual funds in one dashboard.
- Secondary Market Access: Brokers provide access to the secondary market, which helps if you need to sell holdings before maturity.
- Consolidated Reporting: You receive all your tax documents and performance summaries in one place.
- Fees: Some brokerage firms may charge transaction fees when you buy or sell government securities.
Directly from the U.S. Treasury
If you want to avoid transaction fees, you can buy securities directly from the government. The TreasuryDirect website is the official portal for individual investors to purchase and hold these assets.
To begin, create an account and link your bank information for funding. After activation, you can join auctions for new issues. The system supports automatic reinvestment, which rolls your proceeds into new bills after your current bills mature.
Online Platforms
The growth of online investing makes government debt holdings easier to manage. Besides the official government portal, financial technology companies offer simple ways to buy short-term investments.
These platforms often offer better user experiences and mobile app integration than traditional methods. Verify that each platform is a registered broker-dealer so your assets stay protected. With the right method, you can build a reliable income stream with minimal effort.
Treasury Bills vs. Other Investments
Investors weigh the safety of government-backed securities against the growth potential of other assets. Understanding financial markets helps us match each investment with our financial goals. Comparing these options shows when a conservative choice beats chasing uncertain returns.
Comparing with Bonds
It helps to compare short-term bills with longer-term fixed-income securities. While Treasury bills mature in one year or less, treasury bonds often last for decades. Investors use government bonds to lock in interest rates for the long term, while bills support capital preservation and liquidity.
Bills also differ from US Treasury notes. Notes typically mature in two to ten years, creating a middle ground between bills and bonds. Choose between them based on whether you need immediate cash access or steady, long-term income.
Stocks Versus Treasury Bills
Stocks and Treasury bills differ greatly in risk and volatility. Stocks represent company ownership and may grow sharply, but market downturns can cause losses. Bills have the full faith and credit of the U.S. government and support fixed-income securities.
- Risk Profile: Bills are virtually risk-free, while stocks are subject to market volatility.
- Income Structure: Bills provide a predictable return through a discount, whereas stocks may offer dividends.
- Liquidity: Both are highly liquid, but bills offer more stability during economic uncertainty.
| Feature | Treasury Bills | Stocks |
|---|---|---|
| Risk Level | Very Low | High |
| Primary Goal | Capital Preservation | Capital Growth |
| Market Influence | Interest Rates | Corporate Performance |
Ultimately, US Treasury notes and bills provide a defensive shield in financial markets. Stocks may drive growth, while government bonds and bills help portfolios withstand market stress.
The Role of Treasury Bills in the Economy
Beyond individual portfolios, Treasury Bills play a key role in the wider economy. These short-term instruments support federal cash management and help the government meet immediate obligations. By facilitating Treasury borrowing, they help keep public services running without interruption.
Managing National Debt
The federal government uses these securities to cover the gap between tax revenue and daily spending. Backed by the full faith and credit of the United States, they are considered the safest government bonds available. This security makes them a preferred choice for institutional investors holding excess cash.
When the government faces short-term deficits, it issues these bills to maintain liquidity. This process supports national debt management through a predictable repayment schedule. Steady demand keeps the cost of Treasury borrowing relatively low for taxpayers.
Impact on Monetary Policy
The Federal Reserve closely monitors these instruments to assess the health of financial markets. Changes in bill yields often signal shifts in investor views about future interest rates. By adjusting the money supply, the central bank uses these securities to carry out effective monetary policy.
When inflation expectations rise, the link between these bills and other government bonds becomes more important. Investors watch these trends to judge how broader financial markets may respond to rate hikes. Ultimately, debt issuance and monetary policy create a feedback loop affecting mortgage rates and corporate lending.
| Economic Factor | Role of Treasury Bills | Market Impact |
|---|---|---|
| Government Funding | Provides immediate liquidity | Ensures operational stability |
| Interest Rates | Acts as a benchmark | Influences borrowing costs |
| Investor Demand | Serves as a safe haven | Reduces market volatility |
Understanding Returns on Treasury Bills
When we study fixed-income securities, we calculate returns differently from traditional savings accounts. Unlike bonds, which pay periodic interest, these government-backed assets sell below their face value. Our profit equals the difference between the upfront price and the full amount received at maturity.
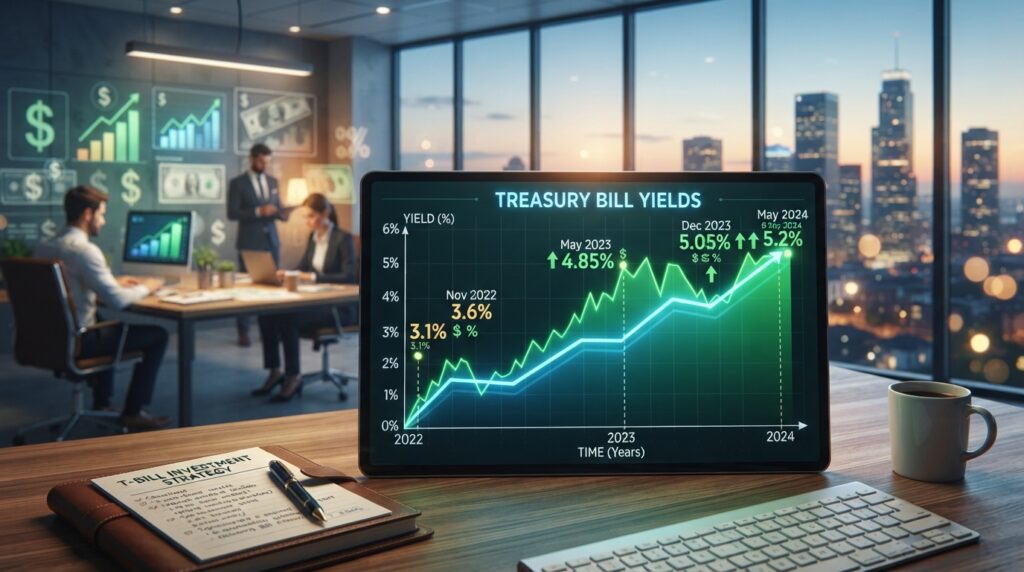
As money market instruments, these assets respond closely to current economic conditions. When market interest rates rise, existing bill prices usually fall to stay competitive. When rates drop, these securities often gain value, affecting the overall Treasury Bill yield.
Yield and Interest Rates
We must separate the quoted yield from our actual dollar profit. The yield shows the annualized return, helping us compare these investments with other financial products. Because these instruments pay no coupon, their yield comes entirely from the purchase discount.
Investors should remember these factors influence the final return:
- Purchase Price: The lower the price we pay, the higher our potential yield.
- Face Value: This is the guaranteed amount we receive at maturity.
- Maturity Period: The time remaining until the bill matures affects how the annualized return is calculated.
Calculating Your Returns
Consider this example: We buy a bill with a $1,000,000 face value for a discounted price of $980,000. This purchase creates a total dollar profit of $20,000 over the investment’s life.
For a bill maturing in approximately 182 days, we can find the Treasury Bill yield by annualizing the profit. Dividing the $20,000 gain by the $980,000 investment, then adjusting for time, gives an annualized return of approximately 4.08%. This calculation shows how efficiently we use capital with fixed-income securities.
By mastering these calculations, we can better understand the landscape of money market instruments. Whether we hold a bill for four weeks or a full year, knowing how to project earnings helps us make informed decisions about our Treasury Bills.
Tax Implications of Treasury Bills
To judge Treasury Bills, look beyond gross yield and find your actual take-home pay. Net returns depend on how tax authorities treat these government securities. Planning for Treasury Bill taxes early helps us compare investment choices wisely.
Federal Taxes
Interest from these securities is subject to federal taxes. We must report this income on our annual federal tax returns. The government treats this interest as ordinary income and taxes it at our marginal tax bracket.
Rates can vary based on our total annual earnings, so we should review our current tax situation. Knowing our bracket helps us estimate the true after-tax yield. Paying this federal taxes obligation is a standard part of owning government debt instruments.
State and Local Taxes
These investments offer tax-exempt income at state and local levels. We pay no state taxes on interest earned from Treasury Bills. For investors in high-tax areas, this exemption can raise the investment’s value against other taxable bonds.
When comparing fixed-income options, calculate the equivalent yield. This shows whether tax-exempt income creates a better net return. Personal circumstances, including our state of residence, guide this analysis. Consider your specific state taxes and financial profile when building a balanced portfolio.
| Investment Type | Federal Tax | State/Local Tax |
|---|---|---|
| Treasury Bills | Taxable | Exempt |
| Corporate Bonds | Taxable | Taxable |
| Municipal Bonds | Generally Exempt | Generally Exempt |
| Savings Accounts | Taxable | Taxable |
Common Myths About Treasury Bills
Government securities are often called perfect, but their benefits and limits are more complex. Many investors think federal backing protects these tools from every financial problem. Yet, no default risk does not remove other market challenges.
Debunking Misconceptions
The main myth says a risk-free asset cannot lose value. The U.S. government has never defaulted on its debt, so this label means no credit risk. It does not promise stable purchasing power over time.
Some people believe T-bills will always beat savings products or high-yield accounts. They offer competitive rates, but another option may pay more during some economic cycles. Compare current yields with other liquid assets before choosing where to keep your money.
Clarifying Misunderstandings
Rising prices create one of the main Treasury Bill risks by reducing your total return. If your return is below the current inflation rate, you face real inflation risk. Your balance may grow, while your buying power for goods and services declines.
People also overlook interest rate changes. When market rates rise, existing securities can fluctuate in value if you sell before maturity. Constant reinvestment also requires active management, so cash does not sit idle.
Knowing these factors helps you create a realistic financial strategy. Treating T-bills as tools, not magic solutions, helps align expectations with market realities. Managing Treasury Bill risks requires understanding how inflation risk and interest rate changes affect long-term goals.
Future of Treasury Bills
Understanding modern finance requires knowing how government-backed assets change. These tools remain a cornerstone for capital preservation as global economic shifts continue.
Market Trends
The Treasury Bill outlook depends on the wider stability of financial markets. Investors often choose these assets as a safe harbor during volatility. These money market instruments help manage cash flow while protecting principal amounts.
Economic Influence
Federal Reserve policy and inflation data strongly shape future yields. We must track these indicators to see whether short-term investments match our personal financial goals. Balancing risk tolerance with current interest rates helps build a resilient portfolio strategy.
We encourage you to review current holdings and consider how these instruments support your long-term objectives. Staying informed about economic shifts helps us make better capital decisions. Please share how you use these assets in your own financial planning.