Did you know that over 100 million Americans use pooled investment vehicles to secure their financial future? This large participation shows these assets support long-term wealth building.
As 2026 nears, smart financial planning can help us navigate the market. These accessible vehicles offer broad portfolio diversification without managing stocks or bonds ourselves.
Choosing the right investment options can help balance risk and reward. Beginners and seasoned pros can use these Mutual Funds as a strategy cornerstone. Let us explore how to improve your holdings for the year ahead.
Key Takeaways
- Pooled assets provide instant exposure to a wide range of market sectors.
- Strategic selection helps manage risk while pursuing long-term growth.
- Understanding fee structures is vital for maximizing your net returns.
- Tax efficiency plays a major role in your overall investment success.
- Professional management saves time for busy individual investors.
What are Mutual Funds and How Do They Work?
Understanding finance begins with learning how pooled investments work. Mutual Funds help people enter stock and bond markets without managing individual securities.
Many investors put money into one fund. This creates a large pool, letting professional managers buy diverse assets that one investor might not afford or understand.
Definition and Basics of Mutual Funds
These funds use a proportional ownership structure. When you invest, you buy shares representing part of the total portfolio. Your gains or losses depend on the fund’s underlying assets.
The process of asset management varies by strategy. In actively managed funds, experts choose when to buy and sell, seeking to outperform the market. Passive index funds seek to match a benchmark, such as the S&P 500, by holding its securities.
These investment options have a unique pricing system. Stocks trade throughout the day, but a mutual fund’s Net Asset Value (NAV) is calculated once each business day. It equals the fund’s total market worth minus liabilities, divided by outstanding shares.
Types of Mutual Funds Available
Investors can choose from many funds designed for different financial goals. These categories help match your portfolio with your risk tolerance and time horizon.
- Equity Funds: These focus primarily on stocks and are designed for long-term growth.
- Bond Funds: These prioritize income generation by investing in government or corporate debt.
- Hybrid Funds: These offer a balanced approach by mixing both stocks and bonds in a single portfolio.
Choosing the right category supports effective asset management. Understanding these investment options helps position your money for future needs. Whether you want aggressive growth or steady income, a fund structure likely fits your strategy.
Benefits of Investing in Mutual Funds
Managing your finances is easier when you use pooled investments. These products offer a clear way to build wealth for new and experienced U.S. investors.
Pooling money gives investors access to opportunities they might otherwise miss. This approach supports long-term financial health through Mutual Funds.
Professional Management
Many people choose funds for expert asset management. You avoid hours of stock research and market watching by relying on a dedicated fund manager.
These professionals study investments that match the fund’s goals. They also rebalance your holdings to keep the strategy aligned with your goals.
“The individual investor should act consistently as an investor and not as a speculator.”
Diversification
Effective portfolio diversification can be difficult for individual investors with limited capital. A single fund can offer dozens or hundreds of companies or bonds.
This strategy helps people focused on retirement saving. It limits the effect of one security’s poor performance on your total wealth.
Spreading risk does not guarantee profits or prevent losses. Market volatility remains a reality for every investor, whatever strategy they use.
Liquidity Advantages
Liquidity gives many investors peace of mind. Most funds let you redeem shares on any business day, so your capital is not locked away.
Many funds also offer passive income through regular dividend or interest payments. This steady cash flow can help people plan for future financial needs.
- Daily Liquidity: Access your money whenever the markets are open.
- Professional Oversight: Benefit from the expertise of seasoned financial managers.
- Broad Exposure: Reduce risk through a wide variety of underlying assets.
Popular Categories of Mutual Funds in 2026
Understanding the many Mutual Funds categories in 2026 helps you match each fund with your financial goals. Choosing the right investment options helps match your money to your risk level and investing timeline.
Equity Funds
Equity funds mainly buy stocks and suit investors seeking long-term growth. They can change in value often, but may deliver strong growth over time.
Many investors use equity funds to build wealth, but expense ratios can reduce your net returns. Learn how to maximize your wealth with a smart investment by balancing these holdings with other assets.
Bond Funds
If you value capital preservation and steady cash flow, bond funds can support your strategy. They invest in government or corporate debt and can provide passive income for your portfolio.
Bond funds can soften market swings when stock prices become unpredictable. High-quality debt can support steady income while lowering your portfolio’s overall risk.
Hybrid Funds
Hybrid funds, also called balanced funds, support portfolio diversification by holding stocks and bonds. This mix offers growth potential while adding some defensive stability.
These funds suit investors who prefer a “set it and forget it” approach to asset allocation. Consider these benefits of a hybrid strategy:
- Automatic Rebalancing: Fund managers adjust the asset mix to keep risk levels consistent.
- Simplified Management: You gain exposure to multiple asset classes through a single investment.
- Enhanced Passive Income: The blend of dividends from stocks and interest from bonds creates a steady yield.
Whether you choose index-based funds or actively managed portfolios, success depends on your broader financial plan. Review each fund’s objectives and fee structures to ensure they support your long-term wealth goals.
Key Factors to Consider When Choosing a Mutual Fund
Informed choices are the foundation of successful long-term wealth growth. During financial planning, your portfolio tools can shape your results. A clear evaluation framework cuts through noise and highlights important factors.
Expense Ratios
The expense ratio is the yearly fee charged by Mutual Funds for operating costs. Even a small difference can reduce compounded returns over decades. We favor funds with low costs and strong quality.
High fees can reduce performance and make benchmark gains harder to beat. Low costs keep more capital invested and working for you. This step supports effective asset management.
Performance History
We seek consistent results, not one year of explosive growth. Compare fund returns with a relevant market index to measure the manager’s value. Short-term spikes can mislead because market cycles favor different sectors.
We review performance during bull and bear markets. A fund showing resilience during downturns may beat one chasing temporary gains through high risks. Review the long-term record to judge the fund’s true potential.
Fund Manager Reputation
The person or team behind the asset management strategy strongly affects fund success. We review the manager’s tenure, investment philosophy, and record in complex markets. Stable leadership often signals disciplined financial planning.
We also ask whether the manager has a significant portion of their own wealth invested in the fund. This alignment of interests motivates the manager to protect and grow all shareholders’ assets. Trusting good leadership matters as much as studying the numbers.
| Evaluation Metric | Why It Matters | Target Goal |
|---|---|---|
| Expense Ratio | Reduces net returns | Below 0.50% |
| Benchmark Alpha | Measures manager skill | Positive consistency |
| Manager Tenure | Ensures strategy stability | Over 5 years |
| Risk-Adjusted Return | Balances growth vs volatility | High Sharpe Ratio |
Top Performing Mutual Funds in 2026
Choosing the right investments can help people seek growth or passive income this year. These examples do not promise future success because past results cannot predict it. Study each strategy carefully before investing money.
“The individual investor should act consistently as an investor and not as a speculator.” — Benjamin Graham
Examples from Large-Cap Funds
Large-cap equity funds often anchor a diversified portfolio. In 2026, FLCOX has gained attention for its steady focus on blue-chip holdings. Technology choices like VITAX also attract interest through high-growth sector exposure.
These funds use professional asset management to handle market changes. Still, look beyond the ticker symbol. Check that each fund’s goal matches your financial goals and risk tolerance.
Notable Mid-Cap and Small-Cap Funds
Mid-cap and small-cap segments can offer strong potential for capital appreciation. Indexed strategies like VTMGX provide broad exposure, while active managers may find hidden value. These market areas often face more volatility than large-cap funds.
When building your portfolio, use this checklist for a balanced approach:
- Evaluate your need for passive income versus long-term growth.
- Assess the role of bond funds to hedge against equity market swings.
- Compare expense ratios to ensure costs do not erode your returns.
- Review the fund manager’s track record during different market cycles.
The best Mutual Funds for you depend on your time horizon. Do not chase the latest trends. A disciplined plan based on your financial goals remains the most reliable path to success.
Understanding Risk Tolerance and Mutual Funds
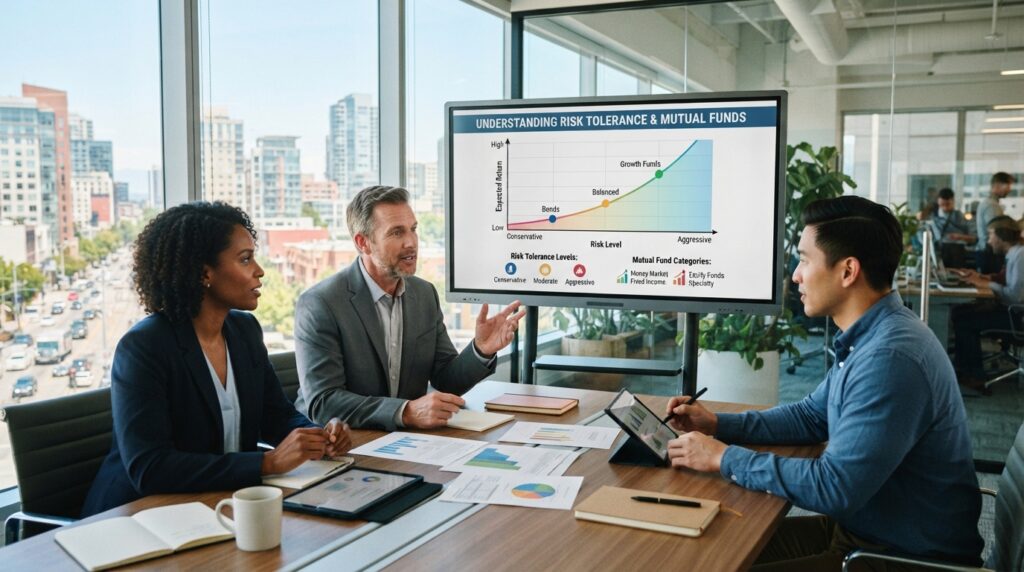
Balancing possible gains and losses is central to effective financial planning. Your portfolio should match your comfort with market changes. This approach can keep your strategy steady during economic uncertainty.
Assessing Your Risk Profile
Your risk profile depends on three factors: your time horizon, income needs, and ability to handle market swings. A long-term retirement saving goal may support more aggressive choices because decades remain to recover from short-term dips. If you need your money within a few years, a conservative approach is usually safer.
Consider how much loss you can endure without leaving your strategy. Portfolio diversification can reduce risk, but it cannot remove risk completely. Knowing your limits helps you stay disciplined during unpredictable markets.
“Risk comes from not knowing what you are doing.” — Warren Buffett
Risk vs. Return Trade-off
Risk and reward shape how Mutual Funds work. Generally, equity funds can offer stronger long-term growth, but prices may change sharply. On the other hand, bond funds usually offer more stability and regular income for people nearing financial goals.
We adjust our asset allocation as our timeline changes. The table shows how time horizons can shape a typical portfolio’s asset mix.
| Time Horizon | Primary Goal | Equity Allocation | Bond Allocation |
|---|---|---|---|
| 35-40 Years | Retirement Saving | 80% – 90% | 10% – 20% |
| 10-15 Years | Wealth Building | 60% | 40% |
| 2-5 Years | Capital Preservation | 20% | 80% |
Proper portfolio diversification can help improve returns while keeping risk manageable. Choose equity funds for growth or bond funds for security. Your strategy should reflect your current life stage and future needs.
How to Start Investing in Mutual Funds
Starting your investment journey can feel clear and empowering with a simple plan. Proper financial planning supports long-term success, whether you focus on retirement saving or building wealth.
Setting Up an Investment Account
Start by opening an account to buy Mutual Funds through a trusted brokerage or fund company. Provide personal identification and link a bank account for transfers. Then choose a lump-sum investment or set up recurring contributions over time.
These trades use the once-daily Net Asset Value (NAV). Your trade executes at the market day’s closing price, so understand this timing when moving money into chosen investment options.
Choosing a Fund to Invest In
Review the fund’s prospectus before choosing an investment. It explains the strategy, fees, and past risks tied to the portfolio. Use equity funds for growth and bond funds for stability, supporting portfolio diversification.
Match your choice with your goals and risk tolerance. A mix of assets can limit market volatility while you pursue your financial goals.
| Investment Strategy | Primary Goal | Risk Level |
|---|---|---|
| Equity Funds | Long-term Growth | High |
| Bond Funds | Income & Stability | Low to Moderate |
| Balanced Funds | Diversified Growth | Moderate |
Success depends on consistency and informed decisions. Review your holdings regularly, then adjust your strategy to support your retirement saving and wider financial planning goals.
Trends Influencing Mutual Funds in 2026
In the current market, two major forces are changing the world of Mutual Funds. These shifts change how we choose holdings and manage our financial portfolios each day.
ESG (Environmental, Social, Governance) Investing
Investors now value personal beliefs alongside financial returns. ESG criteria have grown from a niche interest into a key part of modern asset management.
When reviewing these investment options, examine how funds screen companies. Many managers use rigorous data to confirm holdings match specific environmental or social goals.
Labels can mislead, so examine a fund’s underlying methodology and actual holdings. This helps ensure the fund meets your personal standards.
Technology’s Impact on Fund Management
Technology has changed how we access and manage capital. Automated portfolio rebalancing and advanced data analysis make investment options more accessible than ever.
We see a clear divide between passive index-based strategies and active asset management. Algorithms can lower costs and improve efficiency, but human oversight remains vital during complex market cycles.
The following table shows key differences between traditional and modern management styles in today’s landscape:
| Feature | Traditional Management | Modern Digital Approach |
|---|---|---|
| Decision Making | Human-led analysis | Data-driven algorithms |
| Cost Structure | Higher expense ratios | Lower automated fees |
| Portfolio Access | Broker-assisted | Real-time digital platforms |
| Strategy Focus | Active stock picking | Rules-based indexing |
Technology and ESG integration give us more choices among Mutual Funds. By tracking these trends, we can make better choices that match our financial goals and values.
Common Mistakes to Avoid When Investing
Even experienced investors can make mistakes that hurt their financial planning and portfolio diversification. Market emotions can replace careful research and sound decisions. Understanding these traps helps investors build long-term wealth through Mutual Funds.
Chasing Past Performance
Many investors buy funds simply because those funds performed well last year. Past performance is never a guarantee of future results, yet many investors chase recent winners. This often means buying at the market cycle’s peak, which can sharply reduce your returns.
Instead of chasing short-term gains, study a fund’s results over several years. A fund that handled different market conditions may better support your financial planning goals. Remember, a fund’s current success may already be reflected in its share price.
Not Rebalancing Your Portfolio
Market movements can slowly push your asset allocation away from its original targets. Without rebalancing, your portfolio diversification may become uneven and create more risk than planned. We suggest reviewing your holdings at least once a year to match your risk tolerance.
Rebalancing means selling some assets that performed well and reinvesting in assets that underperformed against your target. This disciplined approach forces you to buy low and sell high, a cornerstone of successful investing. Your intended allocation can protect your capital from unexpected market volatility and keep your long-term strategy on track.
How to Monitor and Manage Your Mutual Fund Investments
After choosing investments, begin monitoring them to keep your goals on track. Effective asset management requires regular attention rather than a set-it-and-forget-it approach. By reviewing your portfolio, you can handle market changes and protect your hard-earned capital.
Regular Review Practices
Review your portfolio thoroughly at least twice a year. Compare current holdings with your original financial planning objectives to confirm they still align. Check whether the fund’s expense ratio increased or its strategy moved from its stated mandate.
Evaluate performance against a relevant benchmark index. If you want to learn how these vehicles work, explore resources on Mutual Funds to deepen your understanding. Also, verify that your asset allocation remains balanced for your risk tolerance.
Knowing When to Exit a Fund
Treat selling a position as a calculated choice, not a reaction to short-term market noise. Consider exiting if a fund underperforms its peers for several quarters. If the fund manager changes or the strategy shifts greatly, it may no longer meet your needs.
Avoid emotional selling during temporary market volatility. Good financial planning targets long-term results instead of daily price changes. When life circumstances change, such as nearing retirement, adjust your asset management strategy toward capital preservation over aggressive growth.
| Review Criteria | Action Required | Frequency |
|---|---|---|
| Performance | Compare to Benchmark | Quarterly |
| Expense Ratio | Check for Increases | Annually |
| Asset Allocation | Rebalance Portfolio | Semi-Annually |
| Fund Strategy | Verify Mandate | Annually |
Tax Implications of Mutual Fund Investments
When you invest in Mutual Funds, learn about taxes before choosing assets. Taxes can reduce your total returns over time, even when markets perform well. Include tax awareness in your financial planning to keep more of your earnings.
Understanding Capital Gains
Mutual funds often pay shareholders capital gains, dividends, and interest during the year. Even when you reinvest these payments, you usually owe taxes for the year they occur. This matters for bond funds, which produce regular interest income usually taxed at your ordinary income rate.
Realized gains happen when a fund manager sells portfolio securities for a profit. The fund passes these gains to you, creating a taxable event. Review your fund’s tax documents each year to understand distribution timing and type, and avoid unexpected tax bills when filing.
Utilizing Tax-Advantaged Accounts
One effective way to manage taxes is to prioritize retirement saving through tax-advantaged accounts. Accounts like a 401(k) or an IRA let investments grow tax-deferred or tax-free. This structure supports financial planning because it shields your passive income from immediate taxes.
With a standard taxable brokerage account, you pay taxes on dividends and capital gains each year. These accounts offer flexibility, but careful management can reduce taxes on your passive income. Consult a qualified tax professional to find account types that fit your goals and circumstances.
Effective tax management is not about avoiding taxes, but about structuring your investments to optimize your after-tax wealth over the long term.
Your strategy should support your broader retirement saving objectives. Whether you hold equity portfolios or bond funds, learn how taxes affect your assets to support financial success.
Future Outlook for Mutual Funds in the U.S.
Navigating the financial landscape requires clear goals. Market predictions for 2026 remain uncertain, but disciplined financial planning can provide a steady anchor. Success comes from consistent habits, not attempts to time the market.
Market Forecasts and Strategy
Investors often weigh long-term growth against capital preservation. People focused on retirement saving often choose diversified equity funds to capture gains over decades. Shorter-term goals may favor bond funds to protect principal from market volatility.
Building Your Financial Legacy
Portfolio diversification means choosing investment options that match your personal risk profile and require due diligence on every fund. Since the Vanguard 500 Index changed the industry in 1976, index investing has become a staple for many. Watch costs and choose quality assets to build reliable passive income through Mutual Funds for patient, informed investors.