Nearly 90% of the world’s millionaires built wealth through property holdings. This figure shows why many people see tangible assets as a path to long-term financial growth. Still, Real Estate Investment returns are never guaranteed, and success requires discipline.
New investors may find building a portfolio overwhelming. They can choose rental ownership, hands-on house flipping, or passive options like professionally managed funds. Learning these starting points helps anyone master real estate investment effectively.
This Real Estate Investment guide offers a practical process for securing your future. We cover clear goals, budgeting, financing options, and due diligence. Smart risk management can help you build a foundation that lasts.
Key Takeaways
- Wealth building through property requires patience and a long-term perspective.
- Newcomers should distinguish between active ownership and passive management options.
- Success depends on thorough due diligence and careful financial planning.
- Market fluctuations are inevitable, making risk mitigation a top priority.
- Strategic financing and budgeting are the cornerstones of a sustainable portfolio.
Set our investment goals before choosing a strategy
Success in property ownership begins before we sign a contract, with a clear vision of our financial goals. We must decide what we want from our Real Estate Investment journey. Do we want quick cash flow or long-term wealth?
Our financial situation helps determine the right path. We should review our available capital, management time, and comfort with risk. A strategy that helps one person could harm another, so we must put our needs first.
To set our direction, we should consider which main goal fits our current lifestyle:
- Monthly Income: Focusing on properties that provide steady rental cash flow.
- Long-term Appreciation: Betting on market growth to increase property value over time.
- Equity Growth: Paying down debt to build ownership stake in the asset.
- Diversification: Adding property to a portfolio to reduce reliance on stocks or bonds.
- Passive Exposure: Using funds or REITs to gain market access without active management.
After choosing our main goal, we can assess our need for cash access. If we need quick access to cash, a long-term Real Estate Investment may not fit. However, stable income and a long time horizon let us lock capital into assets that need patience.
We should avoid generic advice from popular media. Instead, we must build a strategy that reflects our financial reality. Clear goals help each future Real Estate Investment decision support our long-term prosperity.
Compare real estate strategies that fit a first investment
For our first Real Estate Investment, we need a strategy that matches our personal goals. We should weigh effort, liquidity, and control before committing money. A capitalization rate compares income with property value, while due diligence helps protect our interests.
This table shows key differences between common approaches and helps us choose one that fits our risk tolerance.
| Strategy | Effort Level | Liquidity | Primary Goal |
|---|---|---|---|
| Buy and Hold | Moderate | Low | Long-term growth |
| House Hacking | High | Low | Expense reduction |
| BRRRR | Very High | Low | Forced appreciation |
| REITs | Low | High | Passive income |
Buy and hold rental properties
This classic strategy means buying rental properties and holding them long term. We may earn monthly cash flow and see property values rise. It is a simple way to build wealth through housing.
House hack a property we occupy
House hacking means living in one unit of a multi-family property and renting the others. This plan can lower our personal living costs. It is a powerful way to gain landlord experience while reducing housing expenses.
Use value-add and BRRRR strategies
The BRRRR method—Buy, Rehab, Rent, Refinance, Repeat—is an active strategy for forced appreciation. We perform due diligence on distressed properties and find renovations that can raise value. This takes more time and effort but may produce higher returns on our initial cash.
Invest passively through REITs and real estate funds
REITs and private funds offer a hands-off way to access commercial real estate without managing property. These investments offer more liquidity than physical property. However, they may bring more complexity and market volatility than traditional residential holdings.
Choose a market and property type we can understand
Real estate success starts with choosing a location and property type we understand well. Whether we study residential rental properties or commercial real estate, local knowledge gives us an important advantage. It helps us predict long-term demand and tenant stability.
To narrow our search, we must review key signs of a healthy market. We should look for steady job growth and a stable or growing population. Quality schools, useful amenities, local crime data, and current rental trends also matter.
When evaluating investments, we should consider these factors to match our strategy with our goals:
- Employment diversity: A market with multiple industries is less vulnerable to economic downturns.
- Competing inventory: We must assess how many similar units are currently available to avoid oversupply.
- Local infrastructure: Proximity to public transit and major highways often drives long-term value.
Before deciding, we need to learn whether the area supports professional property management. Reliable local help matters if we plan to grow our portfolio or invest from a distance. For more guidance, review this complete investment guide about finding high-potential areas.
Finally, we must calculate the capitalization rate for every property we consider. This metric helps us compare potential returns across neighborhoods and asset classes. Combining local knowledge with financial benchmarks helps protect our capital and support investor growth.
Build a budget for the purchase and ongoing ownership
A complete acquisition budget looks beyond the initial down payment. We must track every dollar to keep our investment profitable over time. It includes closing costs, professional inspections, financing fees, and needed renovations.
Set aside enough reserves for unexpected repairs and capital improvements. These funds provide a safety net when the property needs immediate attention. Without them, one major issue could harm our entire financial position.
A thorough cash flow analysis is essential before any purchase. It shows whether potential rental properties can support themselves during vacancies. Compare monthly income with recurring expenses, including property taxes, insurance, and maintenance.
Ownership costs continue long after closing. Include management fees, landscaping, and periodic upgrades to keep units competitive. Proactive budgeting protects us from changing mortgage rates and rising utility bills.
Detailed cash flow analysis lets us test our investment under different scenarios. This helps our rental properties remain affordable when market conditions change. Preparation is the key to building a sustainable and profitable real estate portfolio.
Select financing that matches our strategy and risk tolerance
Whether we buy a small home or commercial real estate, our financing strategy shapes success. We must compare each loan product with our specific goals. A mismatch between our debt structure and timeline can cause financial strain.
When we begin our Real Estate Investment journey, we have several common options. Each offers benefits and trade-offs involving interest rates, down payments, and repayment terms.
- Conventional Loans: These standard residential loans usually require solid credit and a down payment of 20% or more.
- FHA Financing: These loans suit owner-occupants and allow lower down payments, making them useful for house hacking.
- Private Lending: Individuals often provide these flexible loans, which may carry higher interest rates.
- Hard Money Loans: These short-term, asset-based loans often fund quick flips or renovations, but delays can create major risks.
commercial real estate financing follows different underwriting standards than residential loans. Lenders focus on the property’s income potential, not only our personal credit history. We must provide detailed financial projections and business plans.
| Loan Type | Typical Use | Risk Level |
|---|---|---|
| Conventional | Long-term rentals | Low |
| FHA | Owner-occupied | Low |
| Hard Money | Fix and flip | High |
Finally, higher leverage can increase both our returns and our losses. Borrowing more lets us grow our Real Estate Investment portfolio faster, but raises monthly debt payments. We should keep a buffer for vacancies and unexpected repairs.
Analyze a potential property for cash flow and returns
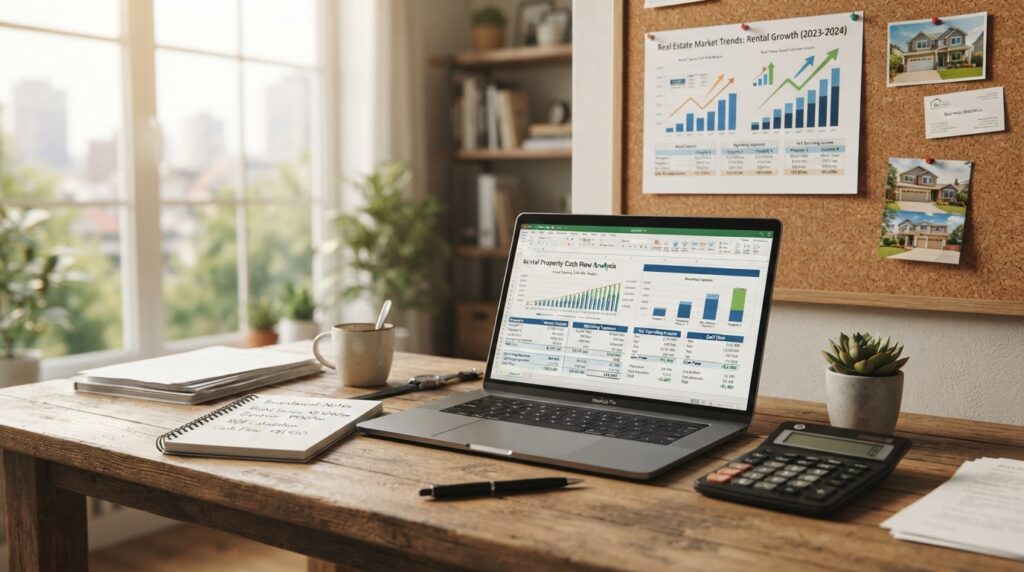
Successful investors use a rigorous cash flow analysis to decide whether a deal makes financial sense. We look beyond curb appeal to understand an investment’s true financial health. Early number checks help us avoid costly mistakes and use our capital wisely.
Estimate rental income and vacancy
First, we research local rental properties to estimate realistic monthly income. We compare nearby listings to learn what tenants pay for similar units. Conservative estimates help prevent us from overstating potential revenue.
We must also account for vacancy rates, or periods when a unit sits empty. Even in high-demand areas, we should allow for a vacancy rate of 5% to 10% annually. This buffer protects our budget from unexpected turnover or maintenance delays.
Calculate operating expenses and cash flow
After estimating gross income, we subtract operating expenses to find Net Operating Income (NOI). These costs include property taxes, insurance, utilities, and routine maintenance. We must include the cost of property management, even if we plan to handle tasks ourselves at first.
Next, we subtract annual debt service, or our total mortgage payments, from the NOI. The remaining amount is our projected cash flow. If it is negative, we must subsidize the property out of pocket each month.
Assess cash-on-cash return and other performance measures
To measure investment efficiency, we calculate the capitalization rate, or cap rate. This metric compares the profitability of different assets, regardless of how we finance them. A higher cap rate generally signals a better return compared with the purchase price.
We also calculate the cash-on-cash return by dividing annual pre-tax cash flow by total cash invested. This percentage shows how hard our money works compared with other investment vehicles. These figures are projections, and actual results may change with market shifts.
Complete due diligence before making an offer
Before committing capital, we investigate the property carefully. This process, called due diligence, protects us from unexpected financial burdens. By checking each detail, we help keep our real estate investing journey profitable and secure.
Review the property’s physical condition
We begin by checking the building’s structure and mechanical systems. Licensed professionals should inspect the roof, foundation, plumbing, and electrical wiring. Never skip these inspections, because they can reveal costly repairs that hurt our bottom line.
When we evaluate commercial real estate, we must also check HVAC systems, parking lots, and fire safety compliance. Environmental assessments can identify hazards such as asbestos or soil contamination. These specialized inspections protect us from long-term liability.
Verify title, leases, permits, and disclosures
Legal documents support our ownership rights. We must confirm that the title has no liens or encumbrances that could threaten the purchase. Reviewing current leases also clarifies tenant duties and income streams.
We also confirm that building permits are current and that the property follows local zoning laws. Sellers usually must disclose known defects. We must read these documents carefully to avoid hidden legal or physical problems.
Confirm insurance, taxes, and local rental requirements
Financial duties extend beyond the purchase price. We must get accurate insurance quotes and verify current property tax assessments. Knowing these ongoing costs helps us maintain positive cash flow.
We also check local municipal codes to ensure the property meets rental requirements. Some cities set specific licensing or safety standards for landlords. Staying compliant from day one prevents future fines and operating headaches.
| Focus Area | Residential Property | Commercial Real Estate |
|---|---|---|
| Physical Inspection | Standard home inspection | Specialized systems & environmental |
| Legal Review | Title and disclosures | Zoning, leases, and permits |
| Financials | Taxes and insurance | Operating expenses & CAM charges |
Decide how we will manage the property
Choosing a property management plan for our real estate portfolio is an important step. We can self-manage, hire a professional firm, or use a hybrid approach. Each option fits different goals and resources.
Self-management gives us full control over expenses and tenant relationships. It often suits owners who live near their investments and can handle maintenance calls. However, we must understand local landlord-tenant laws and follow them.
If we want a hands-off experience, professional property management offers a strong alternative. These experts handle tenant screening, rent collection, and emergency repairs. They charge a monthly fee, but their experience can prevent costly legal mistakes and high vacancy rates.
When we review our rental properties, these factors can guide our decision:
- Time Commitment: Do we have the bandwidth to handle late-night maintenance requests?
- Geographic Distance: Is the property close enough for us to visit on short notice?
- Scale: Are we managing a single unit or a larger portfolio that requires specialized software?
A hybrid model works well for many investors. We can manage leasing and marketing while outsourcing heavy maintenance and emergency response to a third party. This balance gives us direct oversight while reducing our daily workload.
The best choice depends on how willing we are to work with tenants. Successful management of rental properties requires patience and clear communication. Whether we hire help or manage the property ourselves, our primary goals are protecting the asset and maintaining consistent cash flow.
Organize the tax, legal, and insurance requirements
Before we finalize our first property purchase, we must build a strong business foundation. Organizing our legal structure, insurance, and financial records protects personal assets from possible claims. Taking these steps early helps us follow local rules and improve long-term profits.
Choosing the right business entity affects our taxes and legal protection. Many investors choose a Limited Liability Company (LLC) to separate personal finances from investment activities. We should ask a qualified attorney which structure best matches our goals and risk profile.
Good bookkeeping supports a successful real estate portfolio. We need accurate records of income and expenses, including mortgage interest, property taxes, and maintenance costs. These records help us calculate depreciation and find deductible expenses during tax season.
“The hardest thing in the world to understand is the income tax.”
As our portfolio grows, we may enter commercial real estate to diversify our holdings. When we sell a property, a 1031 exchange can defer capital gains taxes by reinvesting proceeds in a like-kind property. This strategy preserves our capital and speeds wealth growth over time.
Insurance is essential to our risk management plan. Our policy must include enough liability protection and property damage coverage for each asset type. A licensed insurance agent can spot coverage gaps before they cause costly problems.
| Requirement | Primary Benefit | Professional Needed |
|---|---|---|
| Entity Formation | Asset Protection | Business Attorney |
| Tax Planning | Expense Optimization | Certified Public Accountant |
| Insurance Policy | Risk Mitigation | Licensed Insurance Agent |
| Record Keeping | Audit Readiness | Bookkeeping Software |
Tax laws and legal requirements are complex, so we should seek qualified professional guidance. A certified public accountant or tax attorney can offer advice for our situation. By staying organized and proactive, we prepare for lasting success in the real estate market.
Protect our investment with reserves and risk controls
Successful investors know risk management supports long-term wealth. During Real Estate Investment, we must prepare for surprises and keep assets profitable.
A cash reserve provides our first defense. We should save money for unforeseen repairs, long vacancies, and major costs, such as roof replacements or HVAC failures. This cushion keeps us from selling assets during a market downturn.
We must also use firm operating controls for our rental properties. Careful tenant screening, regular inspections, and written leases reduce legal disputes and property damage. These steps support steady cash flow and protect our physical assets.
We also need to limit financial risks with conservative leverage and broad insurance coverage. The right policy and manageable deductibles can keep major accidents from wiping out our equity. It is vital to remember that these controls reduce danger but cannot prevent all losses.
Real estate is an illiquid asset class, sensitive to interest-rate changes and regulatory shifts. Disciplined finances help us face these economic cycles with confidence. Staying prepared is the most effective way to protect our future in the market.
Create a practical plan for buying our first property
A successful Real Estate Investment journey starts with a clear plan. It guides us from saving money to final operations. Breaking the process into steps lowers stress, improves success, and builds a strong base before we risk hard-earned capital.
First, we focus on education and consistent saving. We must learn local market conditions and calculate capital for a down payment and emergency reserves. After our finances are ready, lender preapproval helps us seek rental properties within our budget.
After finding a possible target, we perform a careful cash flow analysis to match the numbers with our goals. This checkpoint keeps us from overpaying for an asset that performs poorly. During due diligence, we inspect the building and review every legal document.
After closing, we focus on effective property management. We can manage daily tasks ourselves or hire a professional, but upkeep protects our investment. We should expand our portfolio only after mastering these operating demands.
| Phase | Primary Objective | Key Action |
|---|---|---|
| Preparation | Financial Readiness | Save for down payment |
| Acquisition | Market Entry | Complete due diligence |
| Analysis | Profitability Check | Run cash flow analysis |
| Operations | Asset Management | Implement property management |
This plan turns the goal of owning rental properties into a real, practical outcome. We can start small, perhaps with a house hack, and gain valuable experience. This steady path helps us control our financial future at every step.
Conclusion
Successful Real Estate Investment needs clear goals, careful budgeting, and smart risk management. We might manage rental properties, try house hacking, or use passive REITs. Our strategy should match our available money and time.
Treat each purchase as a long-term commitment, not a quick win. Markets change, and economic cycles can shift property values. Strong reserves and careful research help protect us from repairs or vacancies.
Professional guidance remains important throughout our journey. Tax experts and financial advisors can help us follow complex rules, including 1031 exchange requirements. These tools can offer major benefits, but market risks remain.
We can study these strategies through resources like how to invest in real estate to refine our approach. Patience and current information can help us build equity and reach our wealth goals. Success depends on adapting to new information while following our core financial plan.