More than $25 trillion in public debt is held by investors worldwide. This huge figure shows how investors rely on Government Bonds for financial stability.
At their core, these instruments are fixed-income securities, also called Fixed-Income Securities. We lend money to public authorities and receive regular interest payments called coupons. When the term ends, we usually recover our investment’s original face value.
Understanding how Government Bonds behave helps us build a strong portfolio. We should assess safety, potential income, and tax effects. Inflation and market volatility may also affect long-term returns.
Key Takeaways
- These assets represent a loan from investors to public authorities.
- Investors receive periodic coupon payments throughout the life of the debt.
- The original face value is generally returned upon the maturity date.
- Safety and income are primary drivers for many conservative investors.
- Market risks and inflation can influence the total value of these holdings.
Understanding Government Bonds
Modern finance offers few assets as stable as government-backed securities. These assets anchor many portfolios, helping preserve capital while earning predictable interest.
What Are Government Bonds?
At their core, Government Bonds are loans you provide to a national government. The government promises to repay the bond’s face value on a set date called maturity.
During the bond’s life, you usually receive regular interest payments called coupons. The yield shows your expected total return, based on the purchase price and interest rate. You can buy one bond, but many investors use bond funds for instant diversification.
Types of Government Bonds
Debt instruments differ, so understanding their features matters. Treasury Bonds are backed by the full faith and credit of the federal government, while other options meet different financial goals.
For instance, Municipal Bonds come from state or local governments and often provide tax advantages. Meanwhile, Savings Bonds help individuals save long term with low risk. In contrast, Corporate Bonds come from private companies and carry higher risk, but their higher yields can compensate investors.
| Bond Type | Issuer | Risk Level | Primary Benefit |
|---|---|---|---|
| Government Bonds | Federal Government | Very Low | High Security |
| Municipal Bonds | Local/State Gov | Low | Tax Advantages |
| Corporate Bonds | Private Companies | Moderate/High | Higher Yields |
| Savings Bonds | Federal Government | Very Low | Accessible Savings |
How Government Bonds are Issued
A bond’s lifecycle starts long before an individual investor buys it. Governments use these tools to manage Government Debt and fund vital public infrastructure and services.
This process needs careful planning. Clear terms must serve both the state and the public. Clear rules help authorities maintain trust in the financial system.
The Issuance Process
When a government borrows money, it sets terms for the new securities. These terms include the maturity date, when the principal must be repaid, and the coupon rate, the interest paid to holders.
Most securities are offered through competitive auctions. Large financial institutions often join these auctions to buy the first supply of debt.
Auctions and Secondary Market Sales
After the first auction, the securities enter the Bond Market. This secondary market lets investors buy and sell government bonds that were issued earlier.
Investors price these bonds according to current interest rates and economic conditions. It is important to note that prices and yields move in opposite directions.
A bond priced below face value is a discount bond. It can give the buyer a higher current yield. A bond sold at a premium lowers the buyer’s effective yield.
Understanding these price changes is vital when navigating the Bond Market. By watching these shifts, investors can make informed portfolio choices.
Benefits of Investing in Government Bonds
Government Bonds anchor many conservative investment plans. They offer stability and predictable results during turbulent market cycles. These Fixed-Income Securities can reduce your portfolio’s dependence on stock market performance.
Safety and Security
The main appeal of Government Bonds is their exceptional credit quality. Buying U.S. Treasuries means lending money to the federal government, backed by its full faith and credit. Therefore, they rank among the safest investment options in global financial markets.
No investment avoids price changes completely, but these securities offer security that corporate debt or equities rarely match. They help protect your principal during economic uncertainty. This stability makes them vital to many professionals’ well-rounded, long-term strategies.
Reliable Income Stream
Besides safety, these assets are valued as fixed-income securities that provide steady cash flow. Most bonds pay regular interest, called coupons, until maturity. This predictable income helps you plan your financial future with greater confidence and precision.
At maturity, the government returns the bond’s full face value to the investor. This guaranteed principal repayment gives your capital a clear exit strategy. The table below shows key advantages of holding these assets in your broader investment portfolio.
| Feature | Benefit | Impact |
|---|---|---|
| Credit Quality | High | Low default risk |
| Income | Predictable | Steady cash flow |
| Liquidity | High | Easy to trade |
| Principal | Protected | Capital preservation |
Risks Involved with Government Bonds
Even stable investments, such as Government Bonds, have risks investors should understand. These assets seem safe, but market and economic changes can affect them. Learn about understanding bonds and their risks before investing.
Interest Rate Risk
Interest rate risk is a common challenge for bondholders. When market rates rise, existing Government Bonds usually lose market value. New bonds offer higher payouts, making older bonds less attractive.
This inverse relationship is stronger with longer-term bonds. Selling before maturity may return less than your original investment. Duration helps estimate how a bond’s price responds to changes in the prevailing bond yield.
“The greatest risk in investing is not the volatility of the market, but the risk of not understanding what you own.”
Credit Risk
Credit risk means an issuer may miss interest or principal payments. United States Government Bonds have the government’s full faith and credit behind them. Other sovereign issuers may have different risk levels.
Investors often use agency credit ratings to judge default risk. Even highly rated bonds can lose value before maturity. Market sentiment and the overall Bond Yield environment can affect holdings, regardless of creditworthiness.
Diversification remains the best strategy for reducing these potential risks.
How to Purchase Government Bonds
We can access government debt through several convenient platforms, each suited to different financial goals. Knowing how to buy these assets helps anyone build a stable financial future.
Direct Purchases vs. Brokers
The official TreasuryDirect website is the most common way to buy securities. It lets us purchase Government Bonds and Savings Bonds directly from the U.S. Department of the Treasury without middleman fees.
We can also use traditional brokerage accounts to buy marketable securities in the Bond Market. Brokers may charge transaction fees, but they manage all our investments in one place. This choice suits people who trade often in the active bond market.
“The beauty of direct purchasing is the elimination of unnecessary costs, though brokerage accounts provide superior liquidity for active traders.”
Online Platforms for Buying Bonds
Besides direct portals, online investment platforms offer access to government debt. Many investors buy bond funds or exchange-traded funds (ETFs) holding diverse securities. These choices make interest rate changes easier to manage.
The following table shows the key differences between these purchasing methods:
| Method | Convenience | Transaction Costs | Liquidity |
|---|---|---|---|
| TreasuryDirect | High | None | Low (Marketable only) |
| Brokerage | Very High | Variable | High |
| Bond ETFs | High | Low | Very High |
When entering the bond market, consider your needs. Direct buying suits long-term Savings Bonds purchases. For flexibility, brokerage accounts or ETFs often suit a portfolio of Government Bonds.
- Direct Purchase: Best for long-term, fee-conscious investors.
- Brokerage Accounts: Best for those who want integrated portfolio management.
- ETFs: Best for instant diversification and high liquidity.
Ultimately, your method for buying Government Bonds should match your broader financial strategy. Comparing each platform’s strengths and limits supports informed choices and long-term wealth goals.
Distinguishing Between Short-term and Long-term Bonds
When we compare the range of Government Bonds, investment length shapes our strategy. The time until maturity affects a security’s response to market changes and its possible returns. Understanding these differences helps us match portfolios with our financial goals.
Treasury Bills vs. Treasury Bonds
Treasury bills are short-term investments that usually mature within one year. Their short duration makes them highly liquid cash equivalents. In contrast, Treasury Bonds can last up to 30 years.
These longer-term options often provide a higher bond yield because investors lock away money longer. This Bond Yield can reward investors for accepting that extended commitment.
The payment structure also differs between these debt types. Treasury bills sell below face value, and investors receive the profit at maturity. Conversely, Treasury Bonds pay interest twice a year, creating steady income for decades.
| Feature | Treasury Bills | Treasury Bonds |
|---|---|---|
| Maturity | Less than 1 year | 10 to 30 years |
| Interest Payment | Discounted price | Semi-annual coupons |
| Price Sensitivity | Low | High |
| Primary Goal | Capital preservation | Long-term income |
Investment Horizon Considerations
Our choice should reflect our cash-flow needs and comfort with market changes. If we need money soon, short-term Government Bonds offer stability and protection from sudden price drops. For long-term goals, we might prefer the steady bond yield from longer maturities.
A bond held to maturity behaves differently from one sold early. Selling a long-term security early exposes us to market changes that can affect our total bond yield. Therefore, our investment horizon should match the maturity of the Government Bonds we choose.
Government Bonds and Inflation
When prices rise across the economy, fixed interest payments lose some real value. Even when issuers pay on time, those dollars may buy fewer goods and services later. This creates a special challenge for people who depend on Government Bonds for financial stability.
Impact of Inflation on Bond Values
Inflation acts like a silent tax on fixed-income investments. When prices rise, fixed coupon payments buy fewer goods and services than before. The real bond yield, or Bond Yield after inflation, often falls below the nominal rate.
Investors should know that long-term holdings face greater risk from this trend. As living costs rise, fixed payments become less useful. Therefore, we must assess how changing economic conditions affect our portfolios.
“Inflation is the one form of taxation that can be imposed without legislation.”
Strategies to Hedge Against Inflation
To protect your capital, you might consider Inflation-Protected Securities, including Treasury Inflation-Protected Securities (TIPS). These instruments adjust their principal value when the Consumer Price Index changes. When principal rises with inflation, interest payments increase and help preserve purchasing power.
Other choices can also help manage risk. Floating-rate notes adjust interest payments periodically to match current market rates. A diversified allocation of shorter-term Government Bonds can also limit long-term price volatility.
Together, these tools can help manage your bond yield and protect your wealth. By tracking economic trends, we can adjust our strategy before inflation harms our financial goals. Wise investing takes patience and a proactive response to market shifts.
Tax Implications of Investing in Government Bonds
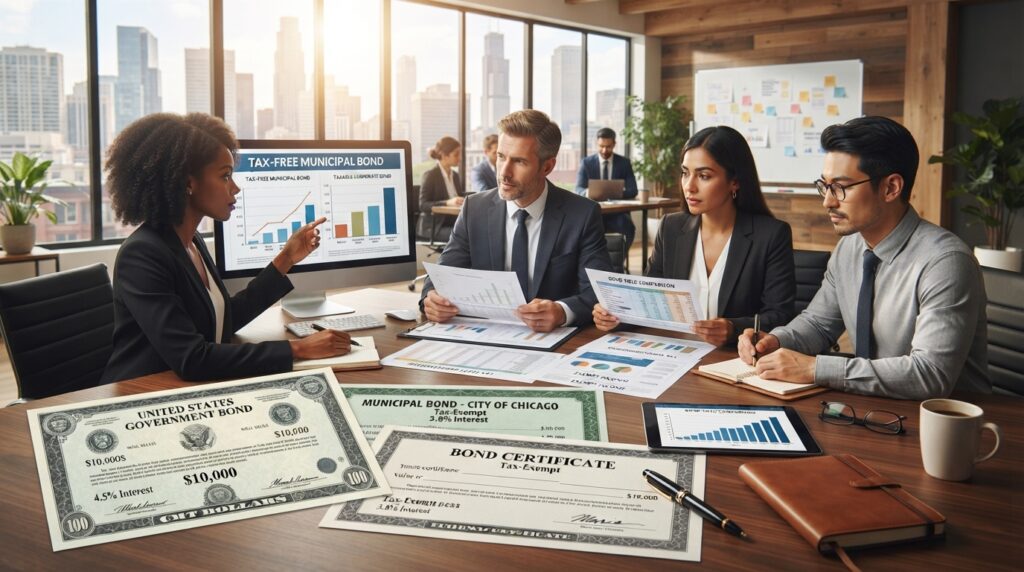
When we invest in debt securities, we must consider how federal and state tax laws affect our returns. The Internal Revenue Service and state authorities may treat interest from each debt instrument differently. Understanding these rules is crucial for calculating your true after-tax return.
Federal vs. State Taxes
Interest from Government Bonds, such as U.S. Treasury securities, is subject to federal income tax. However, these earnings are usually exempt from state and local income taxes. This feature attracts investors who live in high-tax states.
Interest from corporate bonds is generally taxable at federal and state levels. When reviewing your portfolio, compare the interest rate with your tax bracket. This can help your choices match your financial goals.
Tax Advantages of Certain Bonds
Investors often choose Municipal Bonds to reduce their overall tax burden. States, cities, and counties issue these Tax-Exempt Bonds to fund public projects. Their interest is often free from federal income tax, which can help investors in higher tax brackets.
However, tax-exempt income often has lower stated yields than taxable options. Calculate the taxable-equivalent yield to compare tax savings with the lower interest rate. Consult a qualified tax professional before major strategy changes based only on tax benefits.
| Bond Type | Federal Tax | State/Local Tax |
|---|---|---|
| U.S. Treasury Bonds | Taxable | Exempt |
| Municipal Bonds | Exempt | Often Exempt |
| Corporate Bonds | Taxable | Taxable |
Historical Performance of Government Bonds
Reviewing government bonds over the last ten years offers useful lessons for modern investors. Past returns never guarantee future results, but history shows how these assets respond to economic change. Changing interest rates and inflation shape the broader bond market over time.
Trends Over the Last Decade
The last decade brought major volatility to the bond market, driven largely by changing interest rates. When rates rise, existing government bonds usually lose value, creating challenges for long-term holders. Investors watch the bond yield because it signals possible income and risk.
During economic uncertainty, investors often moved toward the safety of government debt. Higher demand often raised prices, even as global markets faced turbulence. Understanding how maturity dates affect price sensitivity remains a crucial skill for anyone managing a fixed-income portfolio.
Comparison with Other Investment Options
Comparing government bonds with other assets shows each one has a distinct role in a diversified strategy. Stocks may grow faster, but they are much more volatile than debt instruments. Corporate bonds usually offer higher yields because they carry more credit risk than government-backed securities.
Cash instruments provide maximum liquidity, but they may not match inflation over long periods. Balancing these assets can help manage risk while pursuing financial goals. The following table compares these common investment vehicles across several key metrics.
| Investment Type | Risk Level | Income Potential | Liquidity |
|---|---|---|---|
| Government Bonds | Low | Moderate | High |
| Corporate Bonds | Moderate | Higher | Moderate |
| Stocks | High | Variable | High |
| Cash Equivalents | Very Low | Low | Very High |
Making Government Bonds Part of Your Investment Strategy
Adding debt instruments to your financial plan starts with clear personal goals. Weigh your time horizon and income needs against the stability these assets can provide.
Building a Balanced Portfolio
Effective Portfolio Diversification combines asset classes to help manage market volatility. Government Bonds can anchor a portfolio when stock markets become unstable. Holding Government Debt creates a buffer, protects capital, and provides predictable interest payments.
When to Add Bonds to Your Investments
Consider adding Fixed-Income Securities when your risk tolerance shifts toward protecting capital. Review maturity dates and yield expectations to match holdings with upcoming financial obligations.
Assess your tax position to select the right instruments and maximize net returns. Monitor your allocation regularly so your strategy stays aligned with long-term wealth objectives.